Which UAE business bank accounts can a company apply for and pay suppliers from without ever booking a branch appointment?
I read the pricing pages and Key Facts Statements of the digital-first providers I could find and shortlisted the 10 accounts below:
TL;DR
- Our top pick is the Pemo Business Account, provided by ruya, for SMEs that already hold a UAE business account and want vendor payments handled alongside their corporate cards.
- Shari'ah-compliant options are available with the Pemo Business Account through ruya, ADIB Business Connect, ADCB's e-Business Account through ADCB Islamic, and RAKstarter's Mudaraba version.
- UP by CBD includes free international transfers on every plan, from AED 49 a month under a six-month offer.
- Zand is the only account here with a minimum balance: companies keep AED 250,000 on average or pay AED 500 plus VAT for that month.
What are the best digital business bank accounts in the UAE in 2026?
Our top pick among the 10 digital business bank accounts in this guide is the Pemo Business Account, provided by ruya.
I picked it for its Bill Pay capability, an accounts payable workflow built into the account itself.
Here’s a complete list of all vendors:
Four things were enough to rule an account out before this list took shape:
- No UAE IBAN in the company's name: payment accounts without one were left out.
- A branch appointment to apply: every account here can be applied for through an app or a web portal.
- Fees shared only on request: each provider below publishes its pricing or a Key Facts Statement.
- Closed to new applicants: E20 by Emirates NBD dropped out because its mobile banking app was discontinued on 1 September 2023.
#1: Pemo Business Account, provided by ruya
The Pemo Business Account is the best digital business bank account in the UAE for SMEs that want supplier payments and idle-cash deposits handled inside the account itself.
Your team pays vendors and funds corporate cards from Pemo's web and mobile apps, without a separate banking login.
ruya, a UAE-licensed Shari'ah-compliant bank listed in the Central Bank of the UAE registry, provides the account itself, with its own IBAN in your company's name.
Disclaimer: A UAE business account is needed before you apply. Pemo opens the Pemo Business Account for companies that already bank in the UAE. An existing business account with another UAE bank is required.
Companies still waiting on their first account will find the Mbank, EDB 360, RAKstarter, UP by CBD, and Yuze entries further down more useful.
For everyone else, opening the account looks like this:
- Timing: typically one to three business days once the documents are complete.
- Documents: Pemo's compliance team confirms what it needs from your company and guides you through it.
- Branch visits and opening fees: neither is involved.
- Incoming payments: customers and parent companies can pay into the IBAN from inside or outside the UAE. Personal and business accounts can both send funds, as long as they're legitimate and meant for business use.
Four pieces make up the account: 👇
Supplier invoices are approved and paid inside the account with Bill Pay
Without payables built into the account, a supplier invoice usually has to be re-keyed into online banking before anyone can pay it.

Bill Pay, Pemo's accounts payable workflow, keeps that whole journey inside the Pemo Business Account.
- Invoice capture: Pemo's AI extracts the details from an uploaded photo or file, or straight from a forwarded email.
- Approval rules: bills route to approvers according to the policy your admins and accountants set up in company settings.
- Batch payments: a whole set of approved bills can go out on a single authorisation.
- Accounting sync: paid bills flow into QuickBooks, Zoho, or Xero already marked as paid.
- Vendor notification: Pemo emails the supplier on your behalf as soon as they're paid.
Local payments go out over Aani, the UAE instant payments platform, typically reaching the recipient within minutes during business hours when under AED 50,000.
Maker-checker controls and fraud checks guard every release
Two familiar accounts payable risks are supplier bank details that have been swapped and invoices that get paid twice.
The Pemo Business Account screens every bill for both before anyone can release it.
- Separate hands on every payment: no single person can take a payment from upload to release.
Your team uploads bills and approvers sign them off, but only the Payment Order Authorizer (POA) can release money, using a one-time SMS code. The POA is usually the owner or an authorised signatory.
- Automatic flags: Pemo marks a duplicate bill, a first payment to a new vendor, or an IBAN that doesn't match the vendor, all before any funds move.
- Purchase order matching: Pemo automatically compares each invoice with its purchase order to confirm everything is correct before any money moves.
- Audit trail: each payment's history, from upload through approval to release, is kept on record.
💡 Keeping preparation and release apart is the maker-checker principle used in corporate banking. In the Pemo Business Account, it applies to every payment.
Wakala terms last between one day and twelve months
Cash your company won't need for a few weeks can go on term with ruya through a Wakala deposit.
Under the Wakala agency model, the company appoints ruya to invest the funds, with expected profit credited at maturity.
Rates vary with the length of the deposit, all quoted as expected profit per annum:
- 1 day and 7 days: 2.50% and 3.00%.
- 1 month: 3.65%.
- 3 months: 3.75%, the highest of the six terms.
- 6 and 12 months: 3.50%.
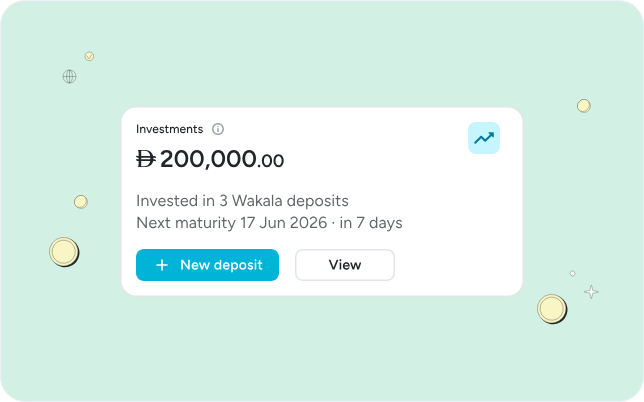
Each deposit can hold between AED 5,000 and AED 5,000,000, with several open at the same time.
Funds are committed for the full term with no partial withdrawals, though a deposit can still be closed early at the cost of its profit.
ruya's Internal Shari'ah Supervision Committee has approved the Wakala structure used.
💡 These rates are accurate at the time of writing and are reviewed regularly.
Card spending comes out of a separate Card Wallet
Pemo corporate cards are funded from the Card Wallet, a separate balance you top up from the Pemo Business Account or from another business account in your company's name.
A transfer from the Pemo Business Account usually lands within 15 minutes, an hour at most, and can go out straight away or on a scheduled date.
Moving money back from the Card Wallet to the account is handled by Pemo support on request, through in-app chat or email.
Pricing
Here are the Pemo Business Account's fees, as listed in our help centre:
- Local transfers: up to AED 50,000, each transfer costs AED 0.50. Above that, the fee is AED 1. VAT is included in both.
- Transfers between ruya accounts: no charge.
- Monthly subscription: AED 200, currently reduced to AED 99. For the first 100 companies, the subscription is waived through December 2026.
- Account opening: free.
- Balance requirements: none, minimum or maximum.
- Wakala deposits: no fee to open or hold one.
Pemo's spend management plans are priced separately, beginning with a free Starter plan and moving to Premium at AED 399 a month per company.
You can apply to open an account or book a call with our team if you'd like to see Bill Pay run against your own invoices first.
Pros and Cons
✅ Payment release always needs the POA, separate from whoever prepared the bill.
✅ Automatic invoice-to-PO validation.
✅ Wakala terms as short as one day.
✅ Free transfers to other ruya accounts.
✅ AED 0 to open, with no balance floor.
❌ You need another UAE business account before applying.
❌ Outgoing payments are AED-only and domestic.
#2: Yuze
Best for: Freelancers and small companies after a low-cost AED account with invoicing and payment links built in.
Similar to: Pemo Business Account, Wio Business.
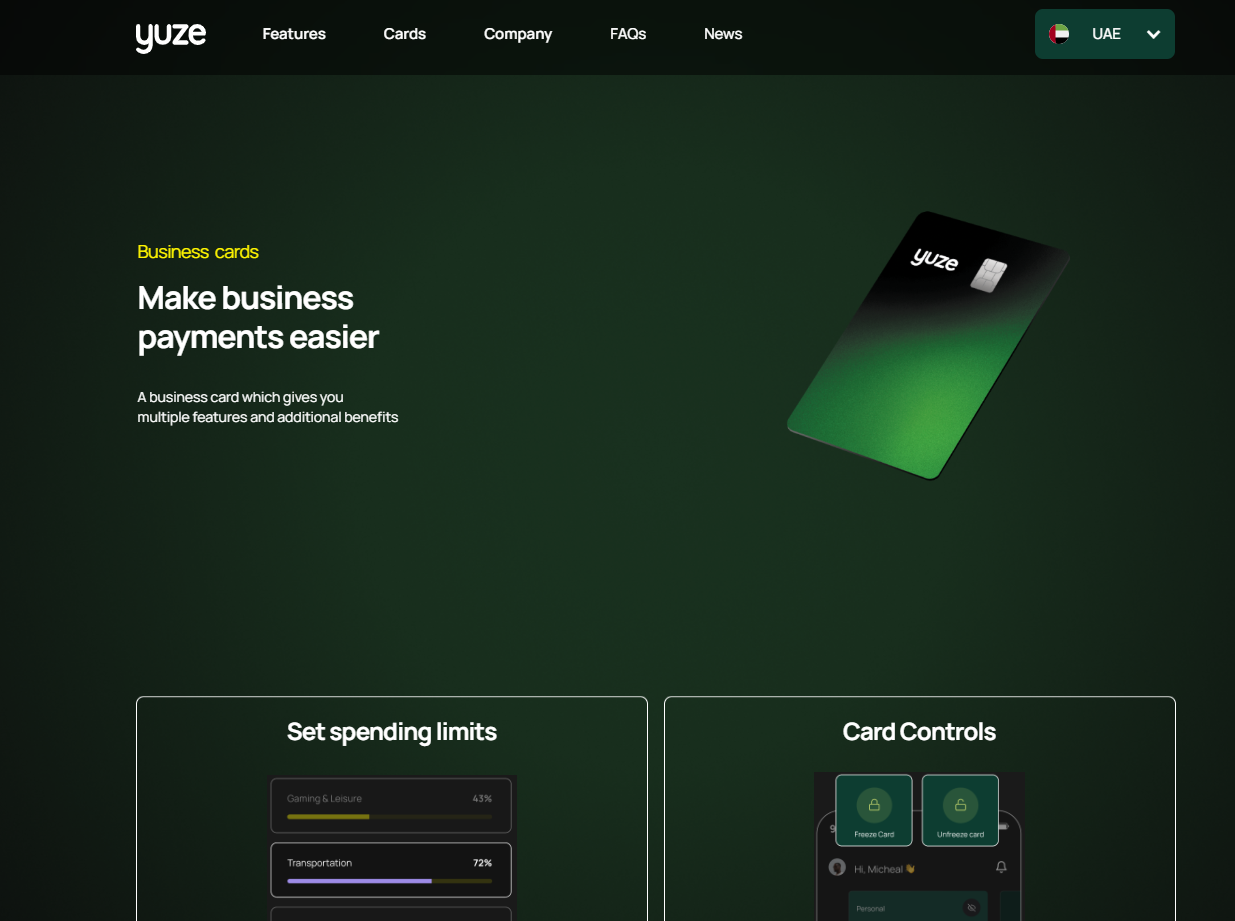
Yuze is a Dubai-licensed business platform whose banking services are provided by Zand Bank PJSC.
Companies with a UAE trade licence can apply, including free zone companies, as can freelancers holding a UAE freelance permit.
Features
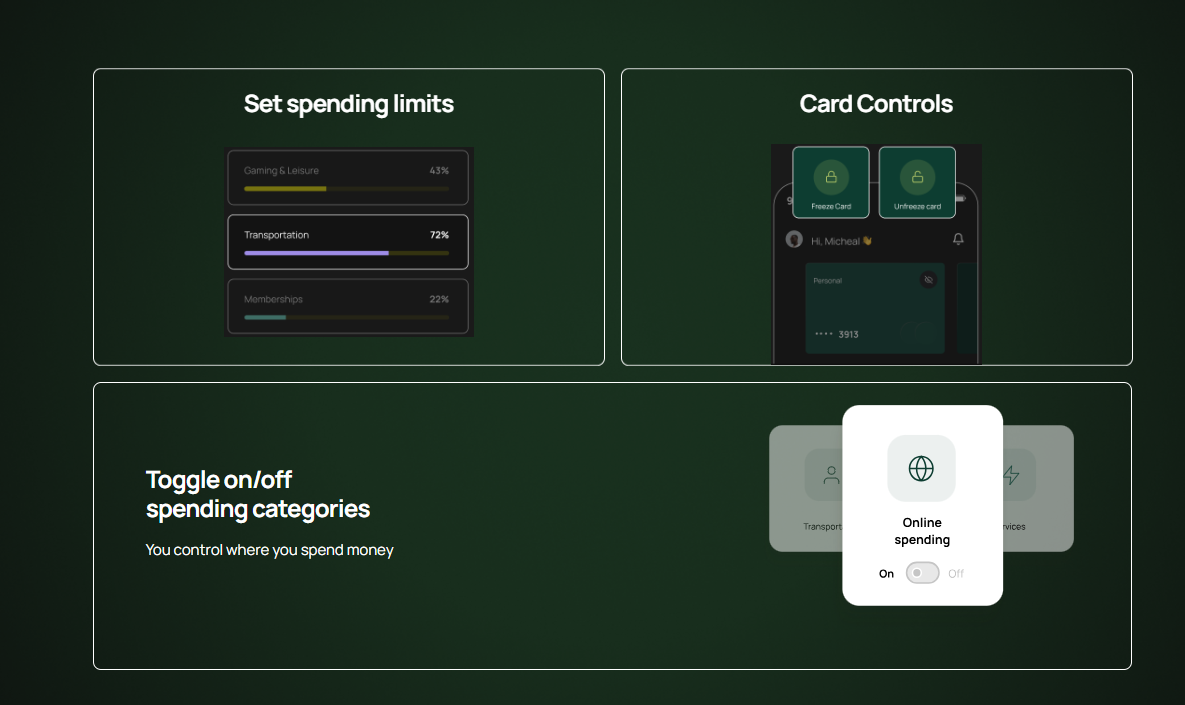
- AED business account with an IBAN: no minimum balance, with funds arriving by bank transfer or payment card.
- Transfers: local transfers to banks and to other Yuze customers, plus international transfers at a per-plan price.
- Invoicing and payment links: invoices can be sent from the app together with a link for the customer to pay.
- Analytics and biometrics: spending analytics on company money and biometric login.
Pricing
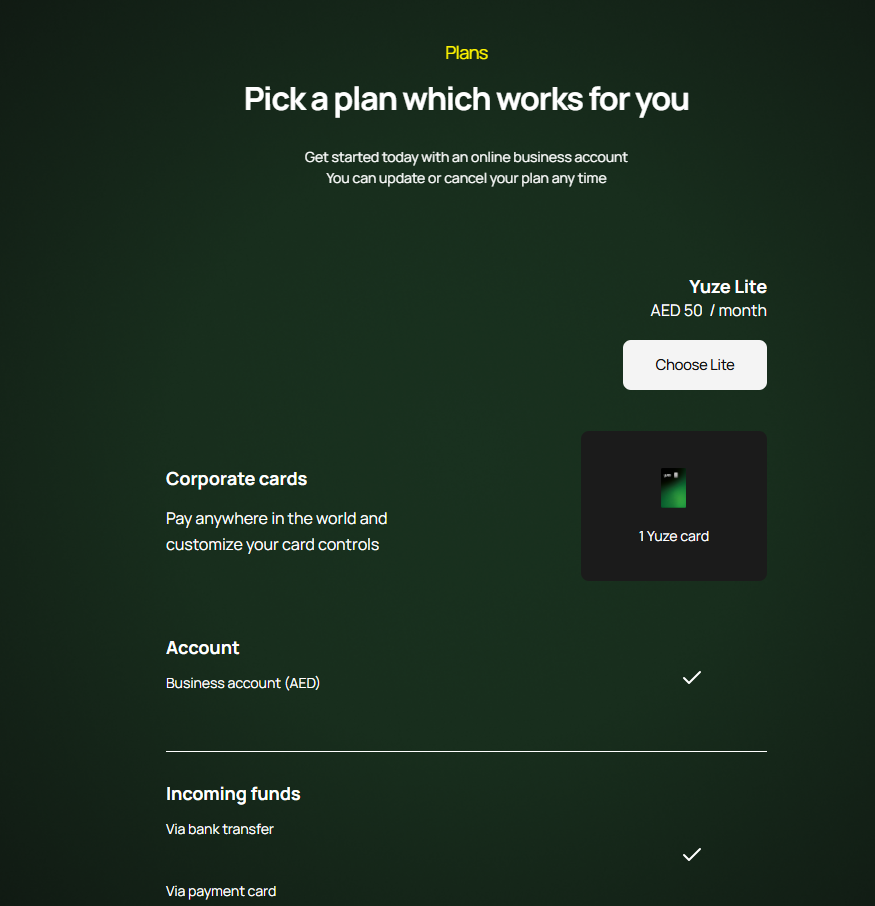
Yuze's UAE plans page currently lists one plan, which can be updated or cancelled at any time:
- Yuze Lite: AED 50 per month.
- Included in the plan: one Yuze card (physical and virtual), card controls, local transfers to banks and other Yuze customers, invoicing, payment links, spending analytics, and chat support.
- Joining fee: a one-time fee upon opening, according to Yuze's FAQ, with the amount not published.
Pros and Cons
✅ Freelance permit holders can apply.
✅ Card controls included, from temporary blocks to transaction limits.
✅ AED 50 a month, with the plan cancellable at any time.
❌ Local transfers only for now, according to Yuze's FAQ.
#3: Wio Business
Best for: Teams where several people need their own login and permissions, and where payroll needs an approver before it goes out.
Similar to: Mashreq NEO BIZ, UP by CBD.
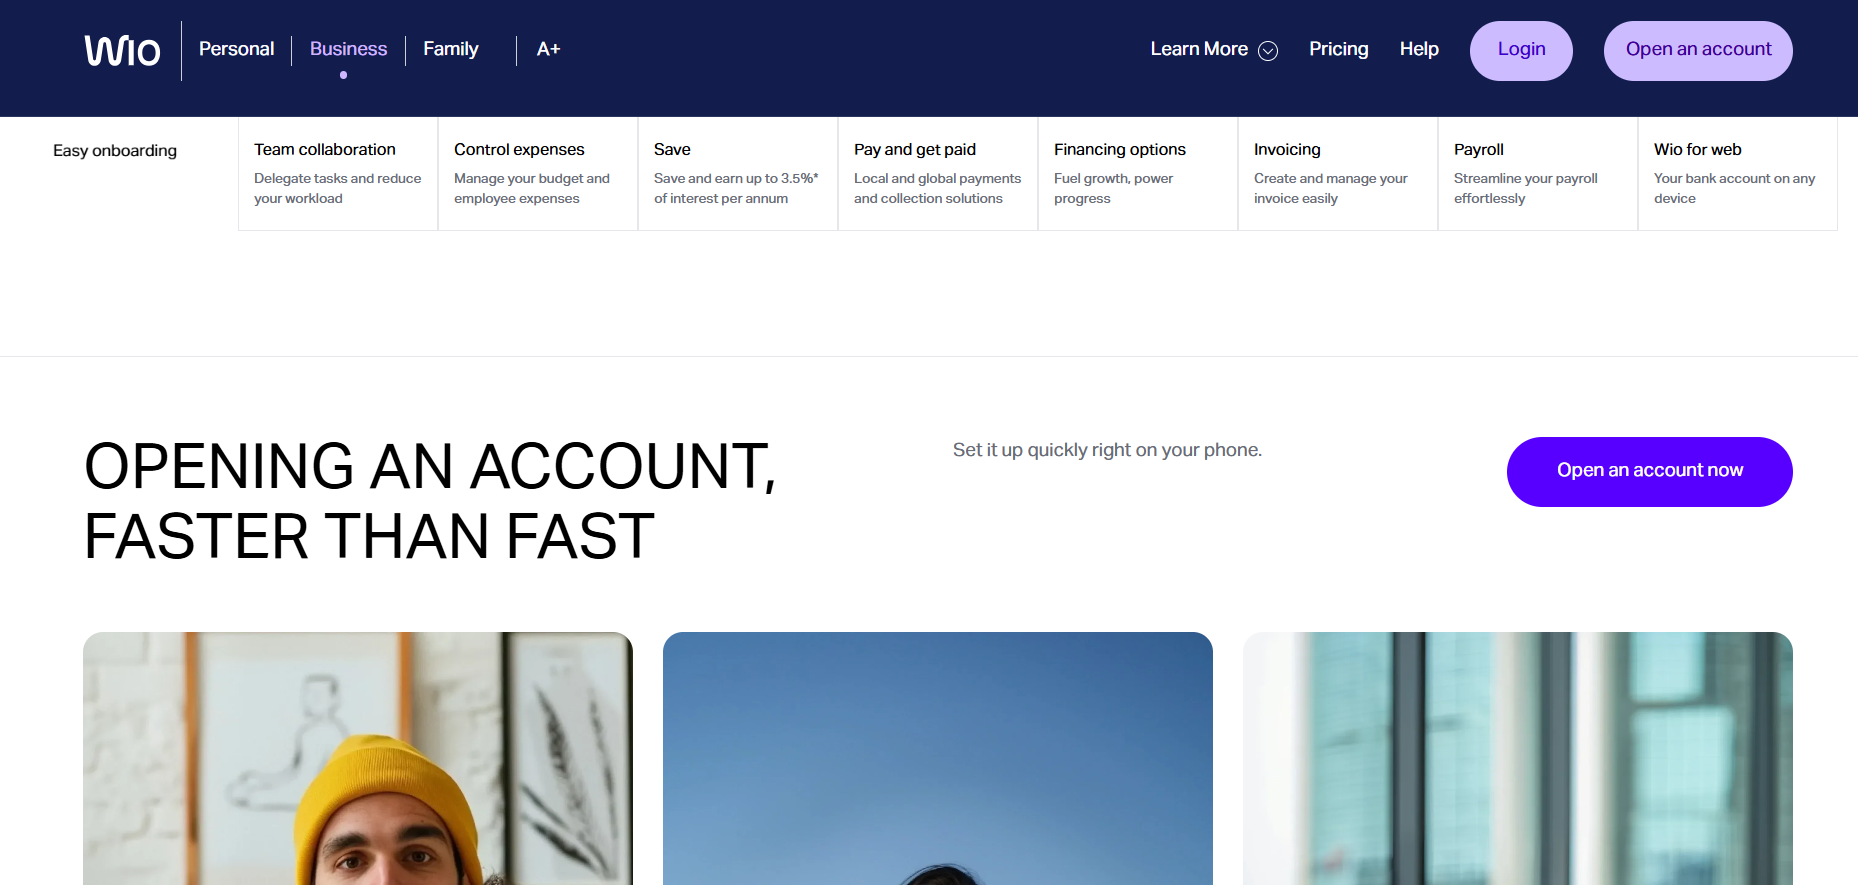
According to Wio, a business account can be up and running in 3 working days, through a fully digital application.
Behind the app is Wio Bank PJSC, which the Central Bank of the UAE licenses and regulates.
Its business page also claims that 1 in 3 new SMEs in the UAE bank with Wio.
Features
- Payroll approvals: salary files can carry an approver step before payment goes out.
- Payment reminders: Wio invoices include payment links through partners such as Stripe, backed by automatic reminders for unpaid invoices.
- Web and mobile: the same account is available in the Wio Business app and on Wio for web.
- Credit and supply chain finance: Wio lists a business credit card, a line of credit, business loans, and supply chain finance.
Pricing
No minimum balance applies to either Wio Business plan.
Wio's Key Facts Statement adds that the first monthly fee is charged one month after account approval.
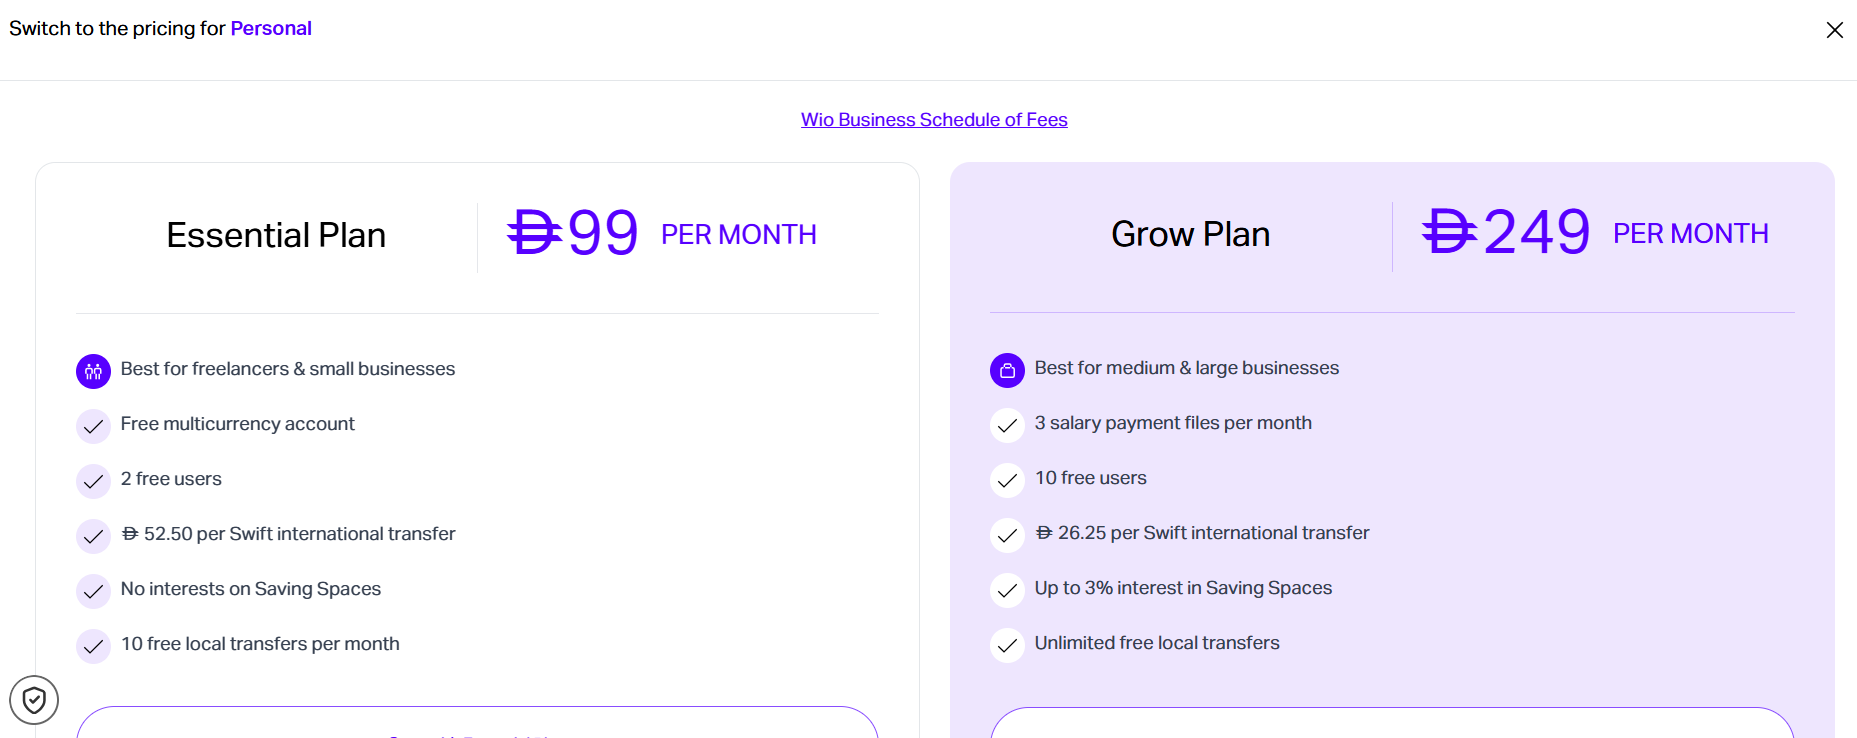
- Essential Plan: AED 99 per month. Includes 1 WPS salary file and 2 free users. The first 10 local transfers each month are free, then AED 1.05 each. SWIFT international transfers cost AED 52.50 each. No interest on Saving Spaces at this level.
- Grow Plan: AED 249 per month. 10 free users, unlimited local transfers at no cost, 3 salary payment files a month, and AED 26.25 per SWIFT transfer. Saving Spaces pay up to 3% for the first 3 months, then 1%. Fixed Saving Spaces reach up to 3.5% per annum on terms from 1 to 12 months.
Pros and Cons
✅ Payroll can require an approver.
✅ No minimum deposit on Saving Spaces.
✅ Wio advertises 24-hour help from real people.
✅ Supply chain finance on offer.
❌ Savings interest is only available on the Grow plan.
#4: Mbank Basic Business Banking
Best for: Startups and SMEs that want a zero-minimum-balance business account from a bank that also offers trade finance and business loans.
Similar to: EDB 360, RAKBANK RAKstarter.
Al Maryah Community Bank, which operates as Mbank, is a Specialized Bank licensed by the Central Bank of the UAE.
Mbank says a business account can be opened in minutes through digital onboarding, with the application completed in a few clicks and no paperwork.
Any UAE-registered business with a valid trade licence can apply, from startups to corporates, free zone companies included.
Features
- Account types: checking accounts, fixed deposit accounts, real estate escrow accounts, and client money accounts.
- Loans and trade finance: working capital loans, term loans, commercial mortgages, and small business loans, alongside letters of credit, bank guarantees, trust receipts, and overdrafts.
- WPS payroll: salary payments through the Wage Protection System, connected directly to the Ministry of Human Resources and Emiratisation, with real-time reporting.
- Cash management: direct debit services, cash collection and delivery, and bill payment services.
- Round-the-clock digital banking: balances, instant transfers, bill payments, and loan applications at any hour, plus a business debit card.
Pricing
Mbank's business page commits to one pricing point for its basic business accounts:
- Minimum balance: none required on basic business accounts.
- Other fees: published in the Fees & Charges section of Mbank's website.
Pros and Cons
✅ No minimum balance on basic business accounts.
✅ Digital account opening in minutes, according to Mbank.
✅ Trade finance and escrow accounts from the same bank.
✅ WPS payroll connected directly to the Ministry of Human Resources and Emiratisation.
❌ Fees aren't summarised on the business page and have to be checked in a separate schedule.
#5: Zand corporate account
Best for: Companies keeping AED 250,000 or more on balance that want to connect their own systems to the bank by API.
Similar to: Wio Business, Yuze.
Zand Bank PJSC holds a Central Bank of the UAE licence and describes itself as an AI-powered bank for the digital economy.
Besides corporate accounts, Zand offers digital asset custody and Zand AED (AEDZ), an AED-backed stablecoin.
Features
- API banking: live balance visibility and payments started from your own systems.
- Escrow services: commercial escrow for milestone-based payments between parties, plus real estate escrow accounts.
- WPS payroll: AED 2 per salary record.
- Security certifications: ISO 27001 and ISO 27701, plus a SOC 2 Type II attestation.
Pricing
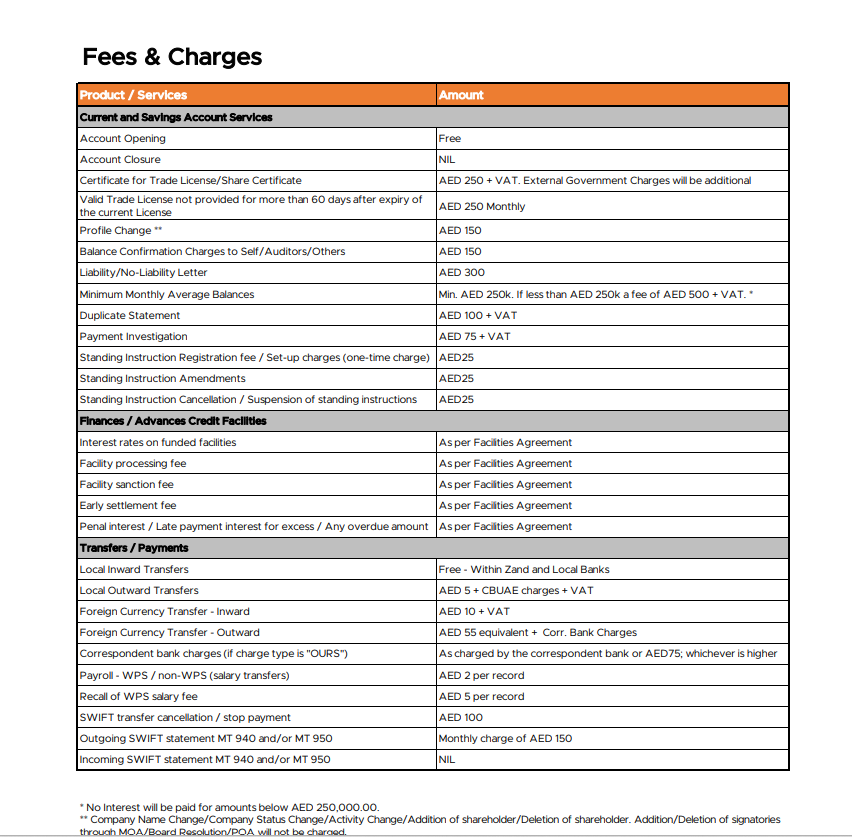
Zand's corporate fees and charges PDF quotes these amounts before 5% VAT, unless stated otherwise:
- Opening and closing the account: free.
- Minimum monthly average balance: AED 250,000. If the average falls below that, a fee of AED 500 plus VAT applies. No interest is paid on amounts below AED 250,000.
- Local transfers: incoming free; outgoing AED 5 plus Central Bank charges and VAT.
- Foreign currency transfers: incoming AED 10 plus VAT; outgoing AED 55 equivalent plus correspondent bank charges.
Pros and Cons
✅ No charge to open or close.
✅ API connectivity with your existing systems.
✅ WPS at AED 2 per record.
✅ ISO-certified security.
❌ AED 250,000 average balance to avoid a monthly charge.
#6: Mashreq NEO BIZ
Best for: Companies fully owned by individuals, with at least one UAE-resident partner or POA, that want a flat-fee account backed by Mashreq.
Similar to: Wio Business, UP by CBD.
NEO BIZ is the online business banking offer from Mashreqbank PSC, which the Central Bank of the UAE regulates.
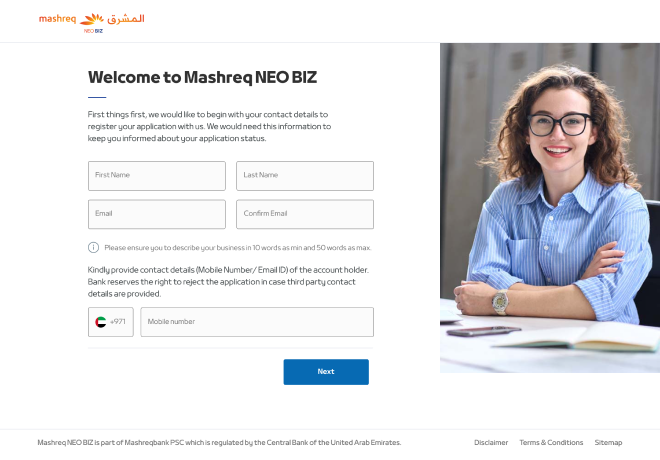
Mashreq can issue the account number and IBAN as soon as an online application is submitted, though the account stays restricted until its reviews are complete.
Features
- Aani enrolment: new business accounts are enrolled in Aani, the UAE instant payments platform, automatically and subject to eligibility, using the signatory's UAE mobile number.
- Multi-currency accounts and SWIFT: Mashreq lists all major currencies as supported, including USD, EUR, GBP, and SAR, with foreign exchange and SWIFT transfers handled online.
- Value-added services: offers on Amazon Web Services, Google Workspace, and Microsoft 365 for new and existing customers.
- Insurance and loans: term life insurance and a business loan facility, both offered through NEO BIZ.
Pricing
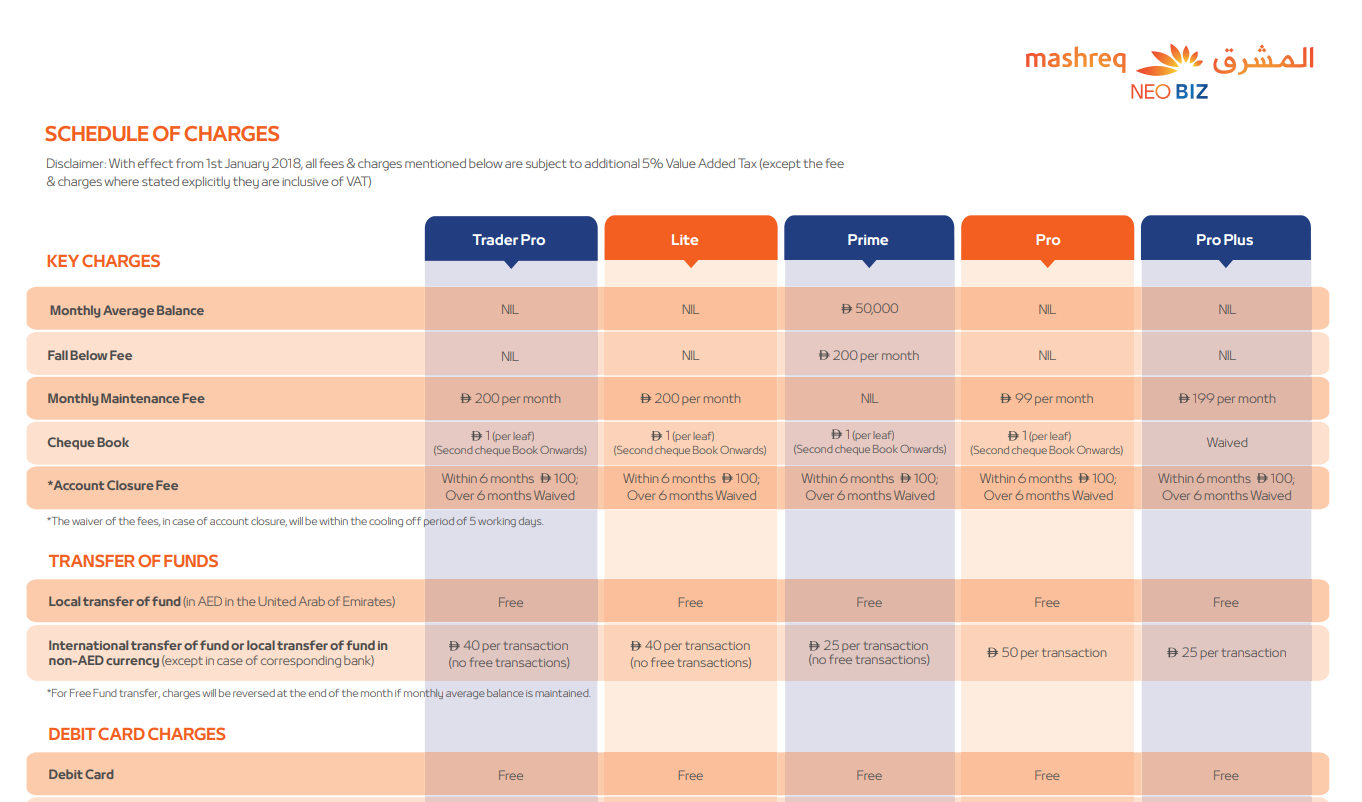
The NEO BIZ Key Facts Statement, version September 2026, prices both plans before VAT.
Neither plan has a minimum balance or a fall-below fee.
- NEO BIZ Pro: AED 99 plus VAT a month. Covers local fund transfers and WPS salary transfers at no extra charge.
- NEO BIZ Pro Plus: AED 199 plus VAT a month. New Pro Plus accounts receive a 3% per annum welcome interest rate on AED and USD balances for the first 90 days after activation. Customers upgrading from an existing Mashreq account don't qualify.
Pros and Cons
✅ Automatic Aani enrolment for new accounts.
✅ Term life insurance available through NEO BIZ.
✅ 3% welcome interest for 90 days on new Pro Plus accounts.
❌ Branch banking is limited, as the Key Facts Statement notes.
#7: UP by CBD
Best for: Small Dubai businesses that want free international transfers included from the entry plan upward.
Similar to: Wio Business, Mashreq NEO BIZ.
Signing up for UP by CBD starts with UAE PASS for identity checks.
For Dubai Unified Licence holders, the DUL number is then enough for the app to fetch the company's details.
Features
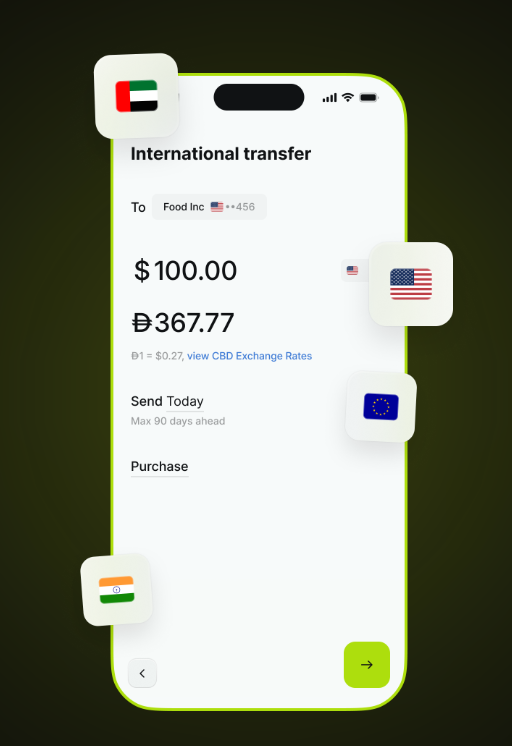
- AED and USD accounts: both currencies are supported now, with more listed as coming soon.
- Real-time payment tracking: local and cross-border payments are tracked live in the app.
- Team card monitoring: team spending and card transactions can be tracked in the app.
- Business credit card: eligible businesses get instant access to one.
Pricing
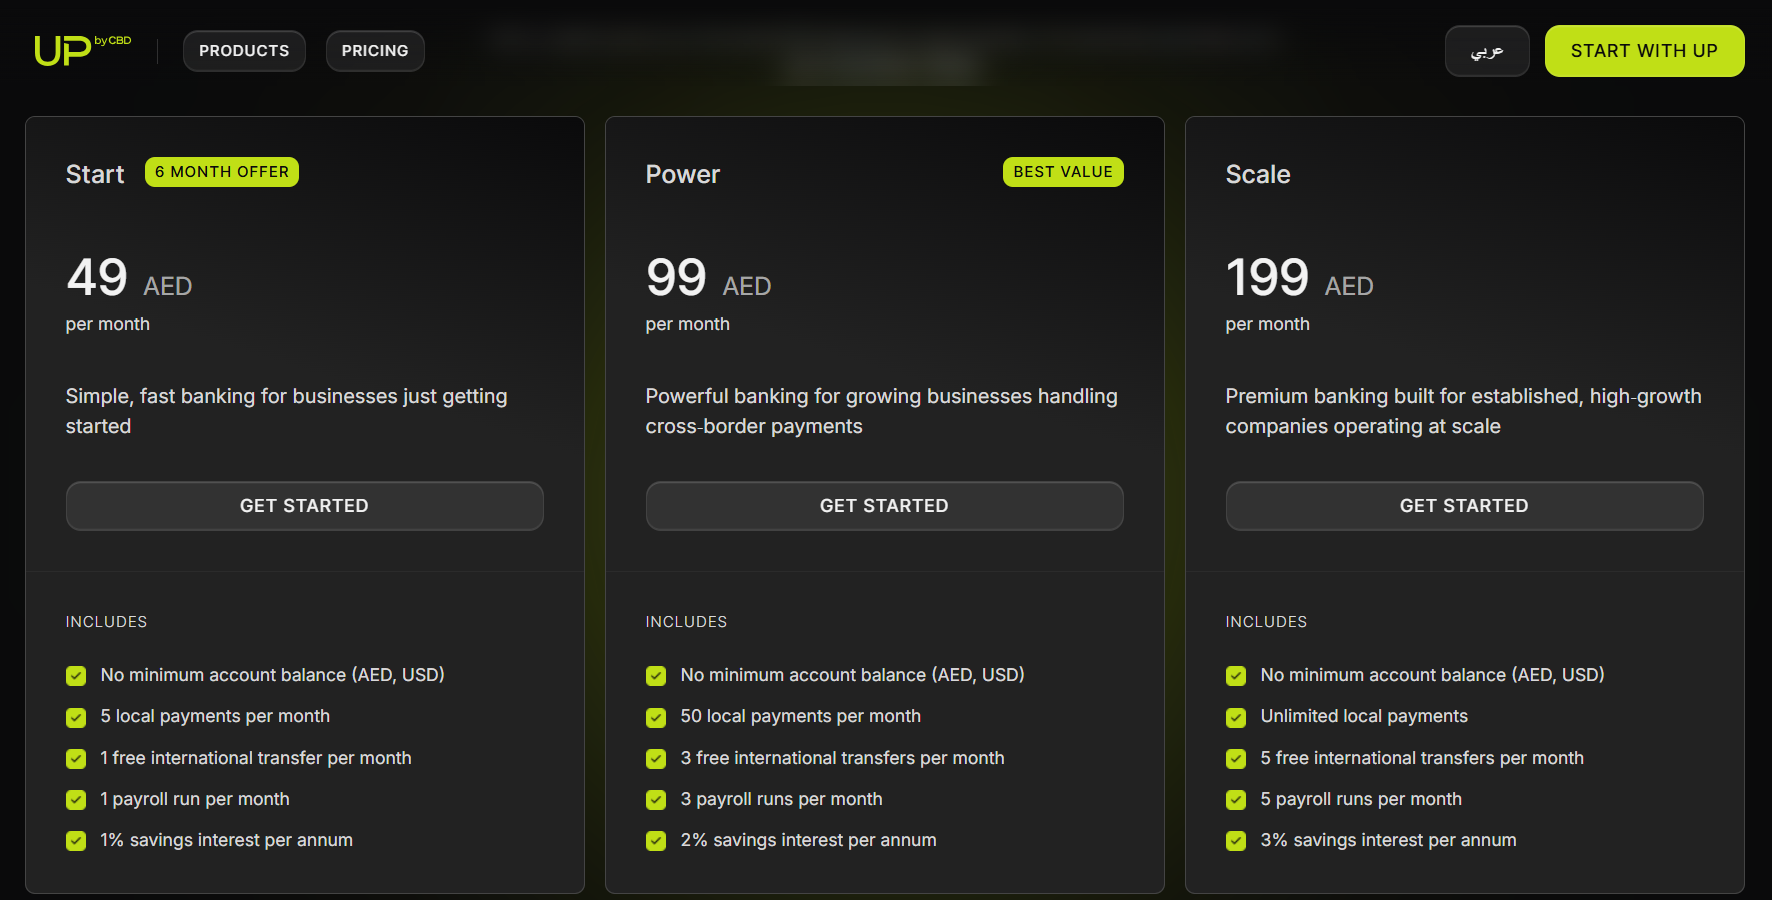
All three UP by CBD plans come with no minimum balance.
CBD's Key Facts Statement and schedule of fees are both dated April 2026.
- Start: AED 49 monthly, as a six-month offer. One free international transfer and 5 local payments a month. Savings interest of 1% per annum.
- Power: AED 99 monthly. The monthly allowance rises to 3 free international transfers and 50 local payments. Savings interest of 2% per annum.
- Scale: AED 199 monthly. Local payments have no cap. Five international transfers a month are free. Savings interest is 3% a year.
Payroll runs grow with the plan, from 1 a month on Start to 5 on Scale.
Pros and Cons
✅ Every plan includes free international transfers.
✅ Payroll runs included in every plan.
✅ Live tracking for each payment.
❌ Start's AED 49 price is a six-month offer.
❌ Launched in July 2026, with little independent user feedback yet.
#8: ADCB e-Business Account
Best for: Emirati and GCC national entrepreneurs holding an e-Trader licence who want a zero-balance AED account with free teller transactions.
Similar to: ADIB Business Connect, RAKBANK RAKstarter.
Abu Dhabi Commercial Bank PJSC, licensed and regulated by the Central Bank of the UAE, designed the e-Business Account for entrepreneurs.
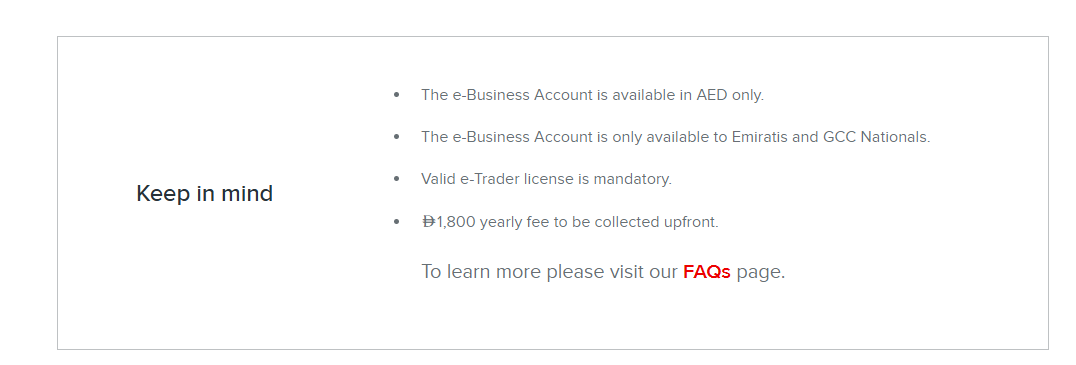
The account is only open to Emiratis and GCC nationals holding a valid e-Trader licence.
Applying starts with an online form, after which a member of ADCB's team gets in touch.
The contact centre and ADCB's branches are other ways to apply.
Features
- International debit card: included with the account.
- Free domestic transfers and teller transactions: ADCB lists both as unlimited and free of charge.
- Digital banking and bill payments: mobile and internet banking, plus a utility bill payment facility.
- Auto sweep facility: available on the account.
- Islamic version: ADCB Islamic offers an e-Business Account approved by its Internal Shari'ah Supervision Committee.
Pricing
ADCB's e-Business Account page lists these charges:
- Yearly fee: AED 1,800, collected upfront.
- Minimum balance: none required for account opening.
- E-statements: free within the statement cycle.
- Cheque books: one free a year.
Other charges are set out in ADCB's e-Business schedule of fees.
Pros and Cons
✅ No minimum balance.
✅ Unlimited free domestic transfers and teller transactions.
✅ International debit card included.
✅ Islamic version available through ADCB Islamic.
❌ Only open to Emiratis and GCC nationals with an e-Trader licence.
❌ The AED 1,800 yearly fee is collected upfront.
#9: ADIB Business Connect
Best for: Sole proprietors and single-owner companies with one signatory that want a Shari'ah-compliant AED account for a flat monthly charge.
Similar to: EDB 360, RAKBANK RAKstarter.
ADIB pitches Business Connect at start-ups and growing businesses that prefer to bank online.
Applying for Business Connect in the ADIB Direct app is limited to sole proprietorships and single-owner companies with one authorised signatory.
Any ADIB business account opened through the app or the online portal also has to belong to a UAE-registered, single-layered company.
ADIB adds that an account number alone doesn't make the account operational, and that a business centre visit may be requested before the account can be used.
Features
- ADIB Direct: the app and online portal used to apply are also ADIB's online banking platform, with no setup or monthly charge.
- Debit card and cheque books: a free Business Classic debit card comes with the account, along with Business Classic cheque books.
- Qard Hasan current account: the current account is held on a Qard Hasan basis, which ADIB's Key Facts Statement describes as a benevolent loan to the bank carrying no profit.
- Reclassification rule: ADIB can move another package into Business Connect after five months with zero branch transactions and at least 10 online transactions a month.
Pricing
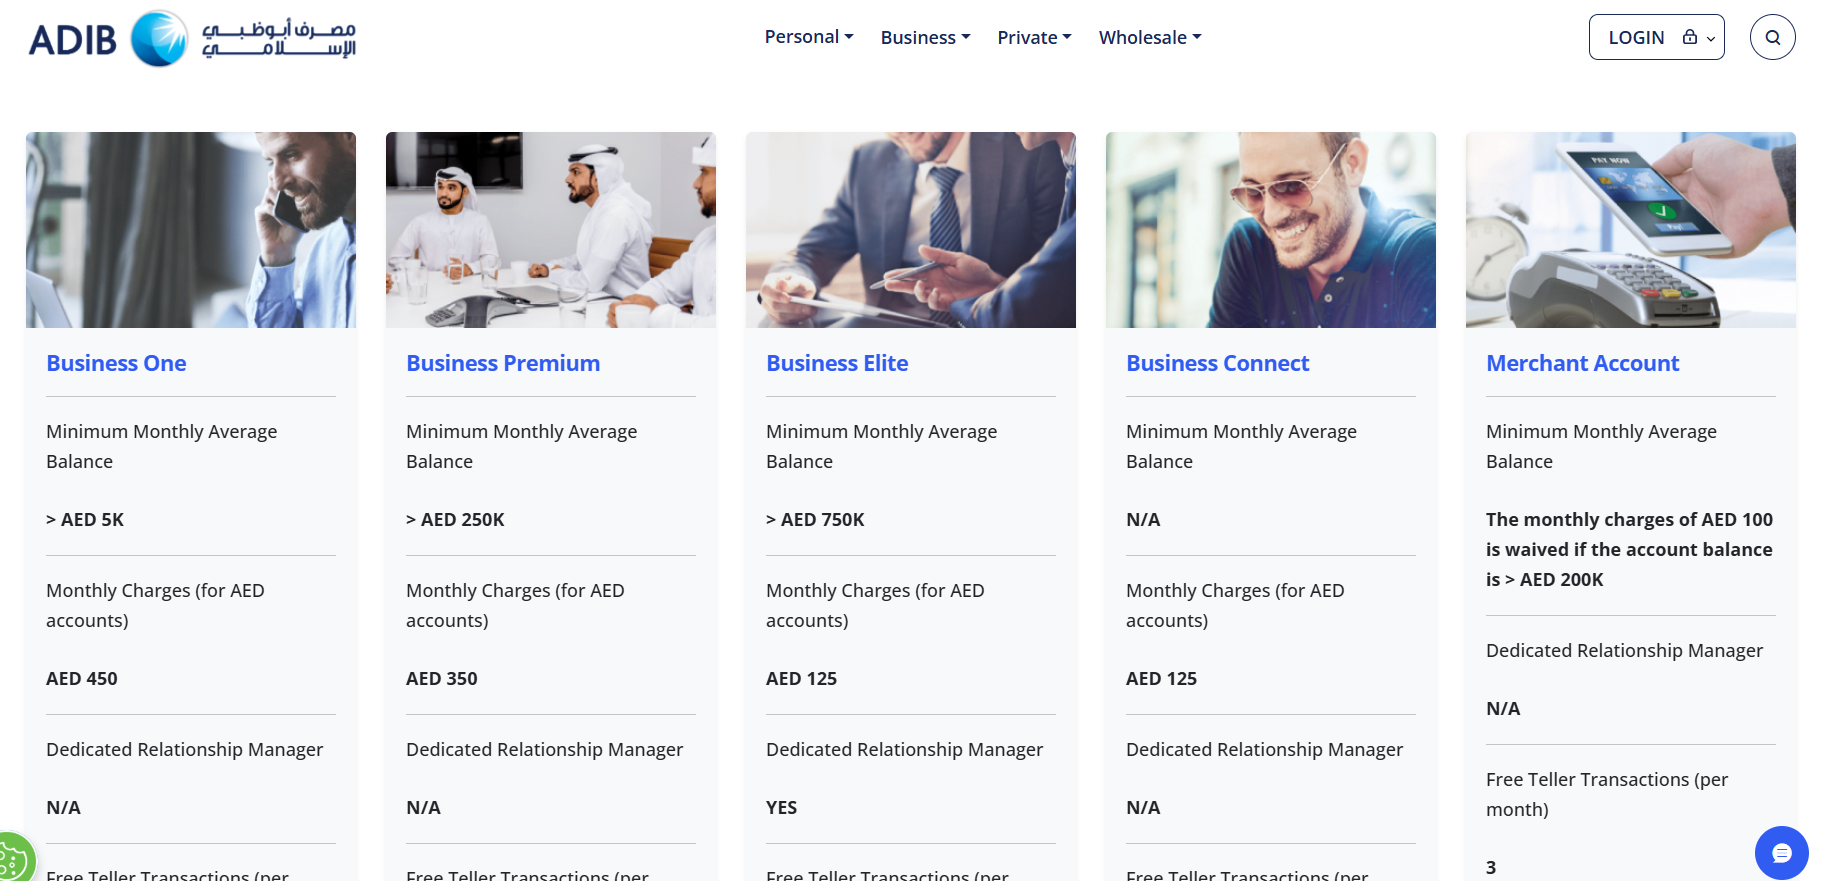
ADIB's package comparison page lists the minimum monthly average balance and the monthly charge for AED accounts:
- Business Connect: no minimum balance, a monthly maintenance fee of AED 125 per account, 1 free teller transaction a month, and AED 50 per additional teller transaction. Available only for business categories that meet ADIB's acceptance criteria.
- Business One: minimum monthly average balance above AED 5,000, monthly charges of AED 450, and 3 free teller transactions a month.
- Business Premium: minimum monthly average balance above AED 250,000, monthly charges of AED 350, and 7 free teller transactions.
- Business Elite: minimum monthly average balance above AED 750,000, monthly charges of AED 125, a dedicated relationship manager, 15 free teller transactions, and preferential FX rates.
- Merchant Account: AED 100 a month, waived when the balance is above AED 200,000, with 3 free teller transactions.
Pros and Cons
✅ Flat AED 125 a month, with no minimum balance.
✅ Shari'ah-compliant.
✅ Free Business Classic debit card.
✅ Cheque books available on the account.
❌ Monthly charges run highest on the smallest tier: AED 450 on Business One above AED 5,000, against AED 125 on Business Elite above AED 750,000.
#10: RAKBANK RAKstarter
Best for: Start-ups wanting a zero-balance account in dirhams, dollars, euros, or sterling, with RAKBANK financing offers available later.
Similar to: Mbank Basic Business Banking, ADIB Business Connect.
RAKstarter is RAKBANK's zero-balance account for new businesses, opened through Quick Apply.
The account is available in AED, USD, EUR, or GBP.
Features
- RAKvalue SME packages: bundled benefits for small businesses. The Plus and Max tiers remove RAKstarter's digital banking fee.
- Chequebooks: one free a year and AED 75 for each extra, issued to eligible customers based on their AECB score and RAKBANK's approval.
- Islamic option: a Shari'ah-compliant version based on Mudaraba is available under the same product name.
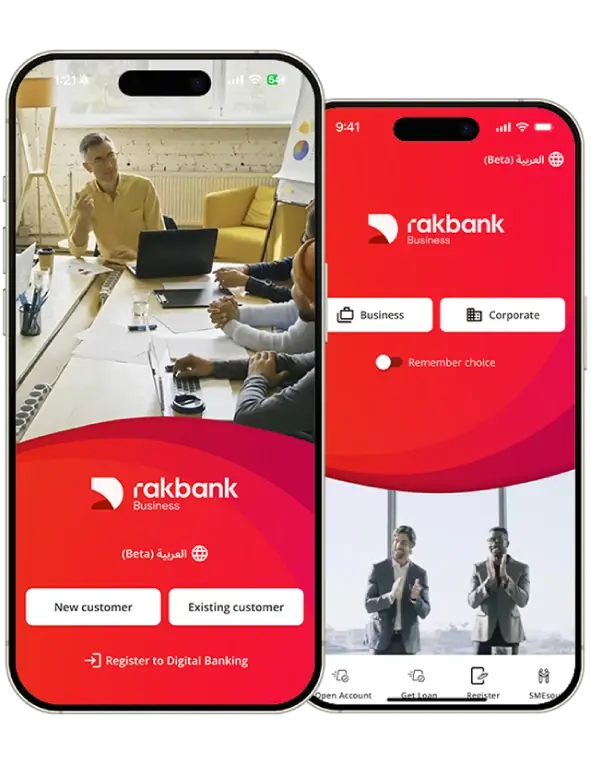
- RAKBANK Business app: payments and payroll handled in one app.
Pricing
RAKBANK publishes its business account charges in a PDF service and price guide, with no plan table on the product pages:
- RAKstarter: no balance requirement, with the monthly account maintenance fee waived for the first month, according to RAKBANK's service and price guide.
- Business Current Account: AED 25,000 minimum average monthly balance, with a monthly fee for not maintaining it and a monthly maintenance fee that is waived at AED 250,000 or more.
- Business Elite: a premium tier for companies holding higher balances.
Pros and Cons
✅ Accounts open within 2 business days of a signed application and complete documents, per the Key Facts Statement.
✅ Financing offers for account holders.
✅ First chequebook each year is free, for eligible customers.
✅ Islamic variant available.
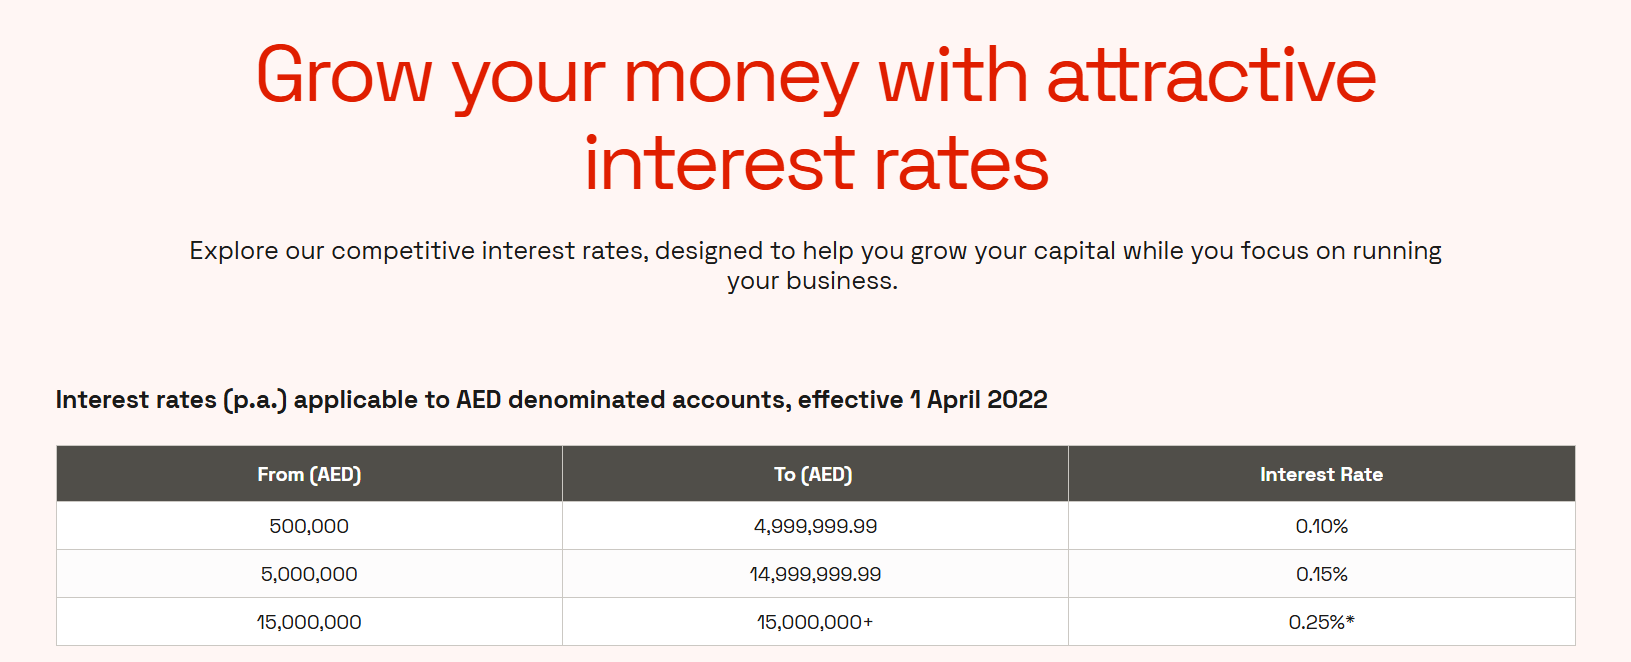
❌ Interest only starts at AED 500,000.
Adding a Pemo Business Account to your banking
For a company that already banks in the UAE, adding a Pemo Business Account brings supplier payments into the same app as its corporate cards.
Bills are uploaded by your team and approved under your policy before the POA releases payment.
Spare cash can go into a Wakala deposit for as little as a day or as long as a year.
You can apply to open a Pemo Business Account or book a call with our team to see why over 10,000 companies in the MENA region have chosen Pemo.
⚠️ Disclaimer: This article was last updated on the 24th of September, 2026. Fees and features come from each provider's published pages on that date and can change. Pemo is a financial technology platform and holds no banking licence; the Pemo Business Account is provided by ruya, a UAE-licensed bank. Expected profit rates are indicative and not guaranteed. This article is general information and not legal, tax, or accounting advice. If there is any misinterpretation of the information, please contact us so we can fact-check it.


