Several UAE banks and fintechs now pitch AI in their business accounts, though what that AI handles varies widely, from identity checks at opening to reading supplier invoices.
Below are the 8 best AI business bank accounts in the UAE in 2026, each reviewed for where its AI is used, its pricing, its main features, and its pros and cons.
TL;DR
- Pemo Business Account, provided by ruya: our top pick, pairing AI invoice reading in Bill Pay with transaction coding by Pemo Copilot.
- Zand and Mashreq NEO BIZ: both use AI to get new business accounts open faster. ADIB Business Connect applies face recognition to the same step.
- ADCB e-Business Account and RAKBANK RAKstarter: AI at the bank level, from ADCB's voice and text app assistant to RAKBANK's AI credit models and its Rai assistant.
- Wio Business and Yuze: most of the documented AI comes from partners, Feedzai and Fiskl in Wio's case and Zand in Yuze's.
What are the best AI business bank accounts in the UAE in 2026?
For 2026, the Pemo Business Account, provided by ruya, takes the top spot, since its AI keeps working on supplier invoices long after opening day.
The table below compares all eight accounts:
How were these AI business bank accounts evaluated?
Three tests decided which accounts made this list:
- The account has to be a genuine UAE business bank account: held at, or provided through, a bank licensed by the Central Bank of the UAE, under the company's own IBAN. It also has to accept new applicants.
- The AI has to be documented: the provider or a named technology partner describes it in product pages, newsroom posts, app listings, executive interviews, sponsored features, or partner case studies. General blog coverage didn't count.
- The charges have to be published: on a pricing page, fees schedule, Key Facts Statement, or FAQ. Yuze is the one partial exception, since its FAQ explains the fee structure without listing amounts.
➡️ A note on scope: the eight accounts range from AI inside payables and bookkeeping to AI used only at opening or in an app assistant.
They're ordered by how directly and recently each provider documents its AI for business customers.
Where a feature is confirmed only for a bank's personal app, or rests on a partner's description, the section says so.
Our guide to AI business bank accounts in the UAE covers how the bank and the software split the work.
#1: Pemo Business Account, provided by ruya
The Pemo Business Account (that's us) offers the best AI business bank account in the UAE for invoice-heavy SMEs, with AI invoice reading and Pemo Copilot coding built in.
Pemo's AI reads each invoice before it reaches an approver, leaving the release decision with your team.
Full disclosure: Even though Pemo is our platform, I've reviewed it against the same criteria as the other seven, gaps included.
Your company's account and IBAN are held at ruya, a UAE-licensed Islamic bank.
Pemo runs everything on top of it, from Bill Pay to corporate cards, in its web and mobile apps.
Disclaimer: Pemo's help centre states that applicants must already hold a business account at a different UAE bank.
Opening the account works like this:
- Turnaround: expect one to three business days from your final document to a working account.
- Paperwork: Pemo's compliance team sends the list of documents your company needs.
- No branch, no fee: the application is fully online and costs nothing to open.
- One login: there's no separate ruya app to manage.
Let's go over the features that put the Pemo Business Account at #1: 👇
Pemo's AI reads supplier invoices in Bill Pay
Bill Pay, the Pemo Business Account's accounts payable workflow, starts with AI reading the invoice.

From upload to payment, a bill moves through these steps:
- AI extraction: Pemo's AI reads the details from an uploaded photo or file, or from a forwarded supplier email, which spares your team from retyping beneficiaries and amounts.
- Approval routing: each bill is sent to the right approvers under the policy set in company settings by your admins and accountants.
- Batch release: approved bills can be released together in one authorisation.
- Paid status in your books: Bill Pay updates QuickBooks, Zoho, or Xero with each bill's paid status.
- Supplier notice: the vendor gets an automatic email once paid.
Local payments travel over Aani and usually arrive within minutes during business hours for amounts under AED 50,000.
Expenses are coded by Pemo Copilot as they come in
Pemo Copilot is the AI that handles bookkeeping across the Pemo platform, card spend included.
Here's what Pemo Copilot takes off your accountant's plate:
- Chart of accounts coding: every expense gets a suggested category and vendor, both editable by your team.
- Learning over time: suggestions sharpen as Pemo Copilot sees more of your history.
- Receipt checks: receipts are matched to transactions by AI, which also flags any that are missing.
- No setup: Pemo Copilot starts working once it's switched on.
➡️ Across the platform, Pemo connects to accounting tools including Zoho Books and Wafeq.
Every payment clears automated checks and a single authoriser
Before money leaves the Pemo Business Account, each bill passes automated fraud checks and waits for one named person to release it.
These controls apply to every payment:
- Duplicate bills: a bill submitted a second time is flagged.
- First-time vendors: paying a vendor for the first time triggers a flag.
- IBAN mismatches: an IBAN that doesn't match is flagged before funds move.
- Separate hands: whoever prepares a payment can never be the person who releases it.
- One-time SMS code: only the Payment Order Authorizer (POA), typically the owner or someone with signing authority, can release money, using a code sent by SMS.
- Audit trail: every action, from upload to release, is logged.
💡 These are automatic fraud checks, which is why this review doesn't count them as AI.
Idle cash can go on term with ruya for as little as a day
A Wakala deposit appoints ruya to invest your money under Shari'ah principles, with the expected profit paid when the deposit matures.
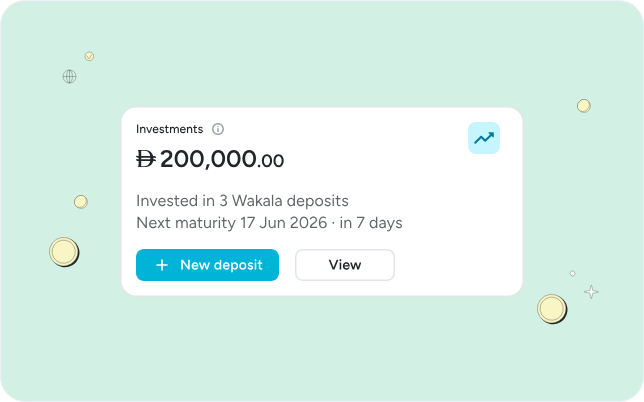
You pick the tenor and move the money yourself, since no deposit is opened automatically.
A few rules apply to each deposit:
- Deposit size: AED 5,000 minimum and AED 5,000,000 maximum, per deposit.
- Several at once: you can hold more than one deposit at a time.
- Early exit: allowed before maturity, though the deposit then pays no profit.
- Partial withdrawals: not possible.
💡 Expected rates follow ruya's terms and conditions and can move with market conditions.
Pricing
Pemo's help centre lists these charges for the Pemo Business Account:
- Monthly subscription: AED 99 for now, discounted from AED 200. Pemo's help centre adds an offer: no subscription fee for the rest of 2026 for the first 100 companies.
- ruya-to-ruya transfers: no fee.
- Local transfers: AED 0.50 per transfer up to AED 50,000, then AED 1, VAT-inclusive in both cases.
- Opening and balances: no opening fee, and no required minimum or maximum.
- Closing: AED 105 within the first six months, free afterwards.
- Lapsed trade licence: AED 262 a month after a two-month grace period.
Pemo's card and expense software is a separate subscription, free on Starter and AED 399 a month per company on Premium.
To see Bill Pay on your own paperwork, book a demo before you apply.
Pros and Cons
✅ AI reads invoices straight from a forwarded supplier email.
✅ Money leaves only after the POA's one-time SMS code.
✅ Overnight Wakala deposits are possible.
✅ Sending money to another ruya account is free.
❌ Applicants must already bank with another UAE bank.
❌ No international vendor payments yet.
#2: Zand corporate account
Best for: Larger SMEs and corporates that can hold a high average balance and want AI agents on their onboarding.
Similar to: Yuze, Mashreq NEO BIZ.
Zand operates as an all-digital bank for corporate, institutional, fintech, and wealth clients.
Alongside its Central Bank of the UAE banking licence, Zand holds VARA approval for digital asset custody.
AI features
- Positioning: Zand's tagline reads "AI-powered bank for the digital economy."
- Zand Agentic AI: aimed at SME onboarding in under 10 minutes, per Zand's June 2026 Qorus submission.
- AI agent platform: planned under an MoU with Alibaba Cloud and Ant Digital Technologies to support customer service and compliance staff.
- Generative AI in operations: an August 2026 fintech.tv interview with CEO Michael Chan covers Zand's rollout of generative AI across banking operations, onboarding included.
Pricing
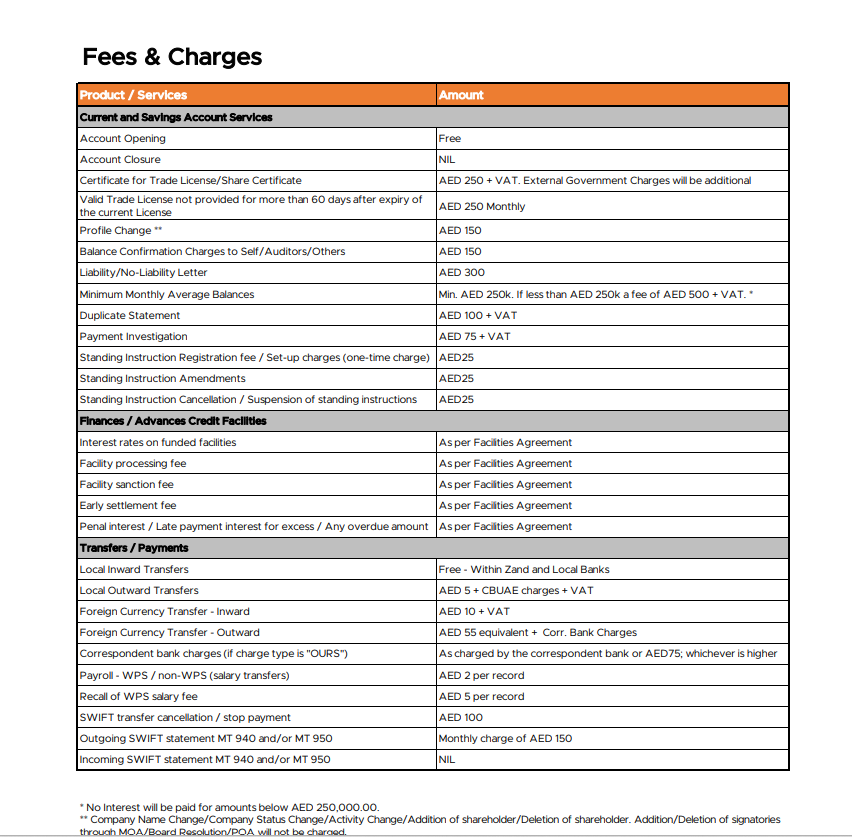
Zand's corporate fees and charges PDF quotes these amounts before 5% VAT, unless stated otherwise:
- Balance floor: AED 250,000 as a monthly average. Months below it cost AED 500 plus VAT.
- Outgoing dirham transfers: AED 5 apiece, with Central Bank charges and VAT added. Receiving is free.
- Foreign currency: incoming transfers cost AED 10 plus VAT. Sending costs the AED 55 equivalent, plus whatever correspondent banks charge.
- Opening and closing the account: free.
Opening and closing an account cost nothing under Zand's fees and charges schedule, which adds 5% VAT to most amounts.
Pros and Cons
✅ Zand Agentic AI on SME onboarding.
✅ Digital asset custody from the same bank.
❌ AED 250,000 average balance to avoid a monthly charge.
#3: Mashreq NEO BIZ
Best for: Companies that need a working account fast, with AED 1,000 cashback for eligible customers if opening takes longer than a day.
Similar to: Zand corporate account, Wio Business.
Mashreq's NEO BIZ comes with a written promise: an account opened in one day, or AED 1,000 back for eligible customers.
The online application takes about 10 minutes, according to Mashreq.
AI features
- AI-driven onboarding: Mashreq's May 2026 announcement ties the one-day promise to AI-driven workflows and electronic KYC, backed by automated routing that cuts manual work.
- Gen AI recognition: Mashreq NEO lists a Best Gen AI Initiative award among its 2026 recognitions from The Digital Banker, without naming the initiative.
- Aani: instant payments appear among the NEO BIZ transfer options.
- NEOPAY bundle: companies that also sign up for NEOPAY receive another AED 1,000 cashback and free ERP software, under Mashreq's terms.
Pricing
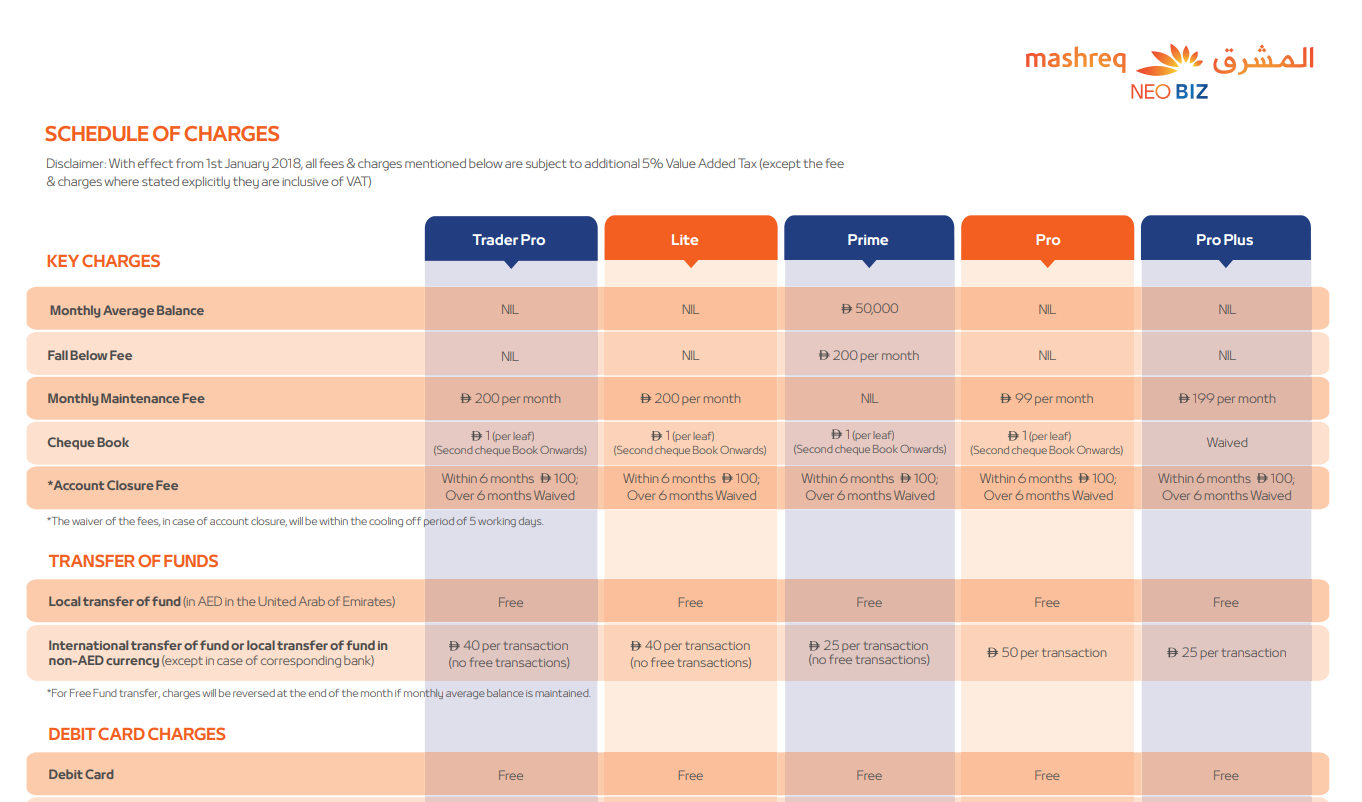
The NEO BIZ Key Facts Statement, version October 2026, prices both plans before VAT.
Neither plan has a minimum balance or a fall-below fee.
- Pro (AED 99 a month plus VAT): the entry plan, with free local and WPS transfers.
- Pro Plus (AED 199 a month plus VAT): new accounts get 3% per annum on AED and USD current account balances during their first 90 days, under Mashreq's terms.
Mashreq asks for no minimum balance on Pro or Pro Plus and charges no fall-below fee.
Pros and Cons
✅ AED 1,000 back if opening misses the one-day mark.
✅ Free ERP software for NEOPAY customers.
✅ Salary files and local transfers at no charge.
✅ No fall-below fee.
❌ Branch banking is limited, as the Key Facts Statement notes.
#4: ADCB e-Business Account
Best for: e-Trader licence holders who want their account in the app ADCB relaunched around an AI assistant.
Similar to: ADIB Business Connect, Mashreq NEO BIZ.
ADCB e-Business Account holders bank through the ADCB Mobile Banking app, which ADCB relaunched in May 2026 as a next-generation app built around an AI assistant.
AI features
- Voice and text assistant: customers can ask it to show balances, send money, handle cards, or track goals.
- Fraud and personalisation: ADCB lists AI-driven fraud detection and tailored recommendations among the app's AI features.
- Statements: e-statements are free for the current cycle.
- Shari'ah-compliant option: ADCB Islamic runs its own e-Business Account.
Pricing
ADCB's e-Business Account page lists these charges:
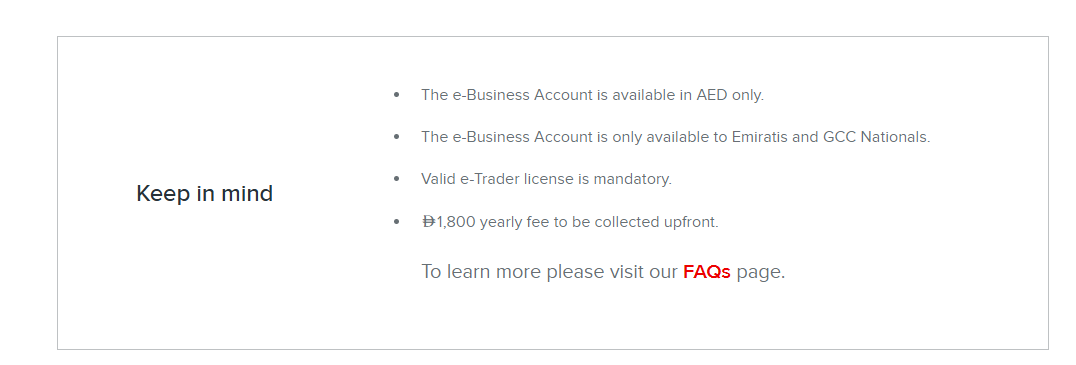
- Yearly fee: AED 1,800, collected upfront.
- Minimum balance: none required for account opening.
- E-statements: free within the statement cycle.
- Cheque books: one free a year.
Pros and Cons
✅ Uses the same app ADCB relaunched around an AI assistant.
✅ Teller visits cost nothing extra.
❌ The AED 1,800 yearly fee is collected upfront.
#5: RAKBANK RAKstarter
Best for: Founders who want an AED 0 balance floor now and a lender using AI credit models later.
Similar to: ADCB e-Business Account, Yuze.
RAKBANK, which calls itself the UAE's go-to SME bank, offers RAKstarter as its zero-balance entry account.
Applications go through Quick Apply, the same online portal RAKBANK uses for business finance requests.
AI features
- AI-powered credit models: RAKBANK is adopting credit models that draw on transaction and supply-chain data for SME financing, according to a Khaleej Times supplement on RAKBANK's SME business.
- Rai digital assistant: RAKBANK's app listing introduces Rai for instant answers in the RAKBANK app.
- Azure OpenAI: Microsoft's May 2025 case study describes RAKBANK's in-app assistant running on Azure OpenAI and pointing customers to the feature they ask for.
- Business login check: Rai is confirmed for the RAKBANK app. Ask RAKBANK whether its business online banking and business mobile app offer it too.
Pricing
RAKBANK publishes its business account charges in a PDF service and price guide, with no plan table on the product pages:
- RAKstarter: no balance requirement, with the monthly account maintenance fee waived for the first month, according to RAKBANK's service and price guide.
- Business Current Account: AED 25,000 minimum average monthly balance, with a monthly fee for not maintaining it and a monthly maintenance fee that is waived at AED 250,000 or more.
- Business Elite: a premium tier for companies holding higher balances.
Pros and Cons
✅ Zero-balance account.
✅ AED 1 per online dirham transfer.
✅ Finance applications through the same Quick Apply portal.
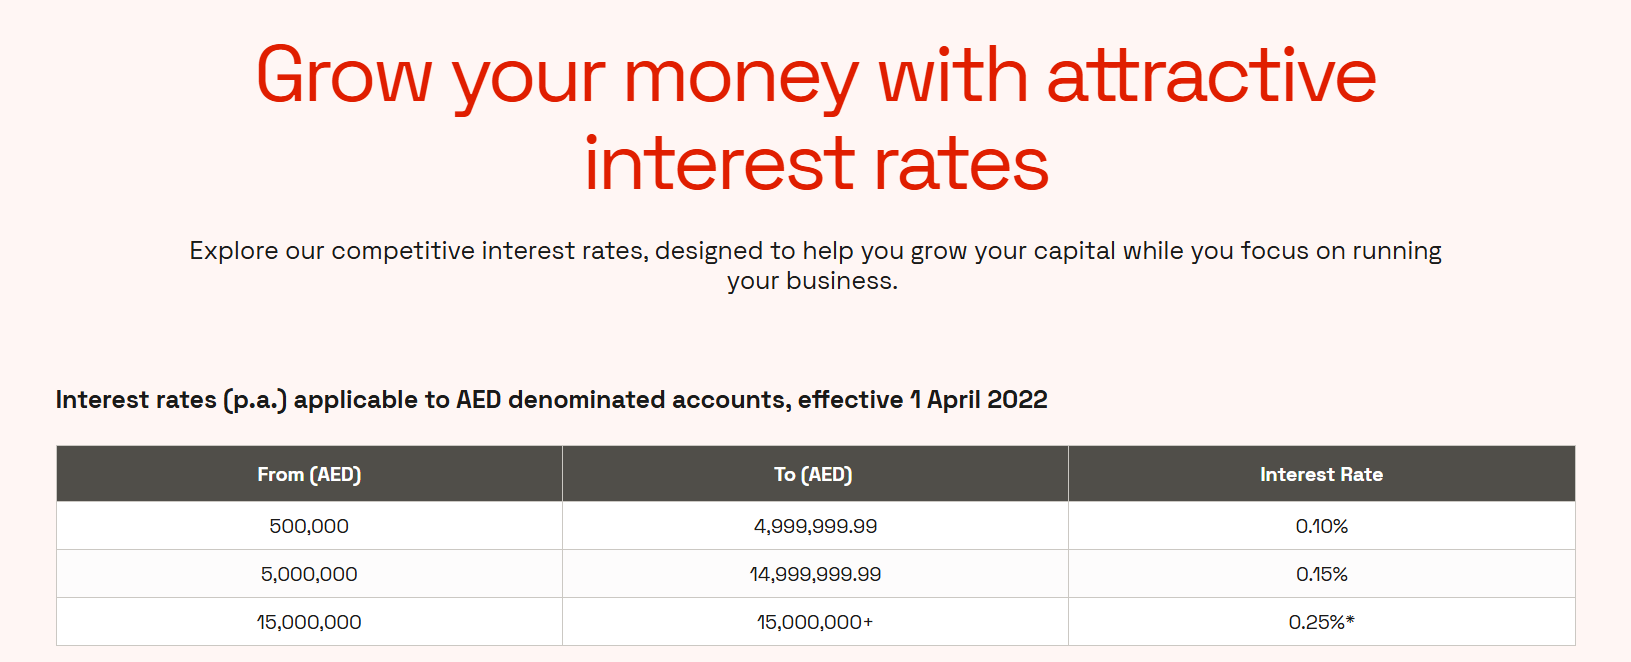
❌ Interest only starts at AED 500,000.
#6: Wio Business
Best for: Businesses already using Fiskl or Wafeq that want their bank feeding those tools directly.
Similar to: Pemo Business Account, Yuze.
Wio Business was Wio Bank's first product, launched a year before Wio Personal.
AI features
- AI fraud detection: Wio's Head of Fraud Risk told Feedzai that the AI and machine-learning capabilities of its fraud tools impressed the team.
- Fiskl's AI engine: categorises Wio transactions and reconciles them inside Fiskl.
- AI pilots: Wio Bank says it runs AI pilots across its operations, with early efficiency gains.
- NVIDIA Inception: Wio Bank joined the program in January 2026 to speed up AI work across the bank.
Pricing
No minimum balance applies to either Wio Business plan.
Wio's Key Facts Statement adds that the first monthly fee is charged one month after account approval.
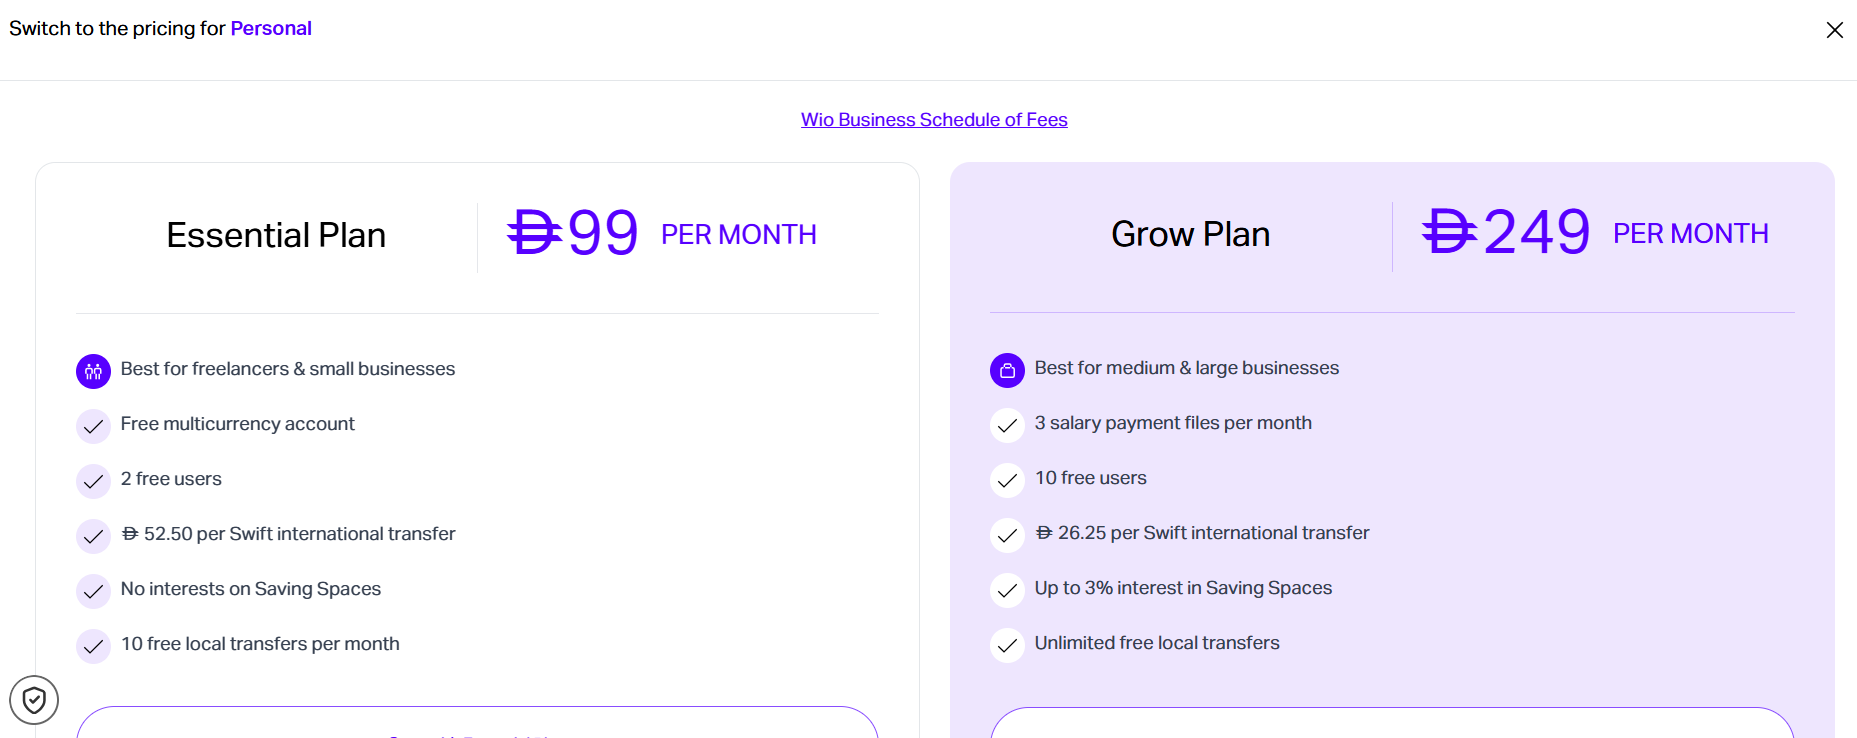
- Essential (AED 99 a month): two users and ten free local transfers a month are included. Each SWIFT payment abroad is AED 52.50.
- Grow (AED 249 a month): 10 free users and unlimited free local transfers. The plan includes 3 salary payment files monthly and cuts SWIFT to AED 26.25. Saving Spaces interest starts at up to 3% for three months before dropping to 1%.
Pros and Cons
✅ Direct bank feed into Fiskl and Wafeq.
✅ Accountants can queue payment requests for your sign-off.
✅ Unlimited free local transfers on Grow.
✅ Both plans are priced on Wio's website.
❌ Savings interest is only available on the Grow plan.
#7: ADIB Business Connect
Best for: Sole owners who want to apply for an Islamic business account from a phone.
Similar to: ADCB e-Business Account, Pemo Business Account.
With more than 94% of ADIB's transactions happening on digital channels, Business Connect is the bank's online-first business account.
The ADIB Direct app accepts Business Connect applications from single-owner businesses that have one authorised signatory.
AI features
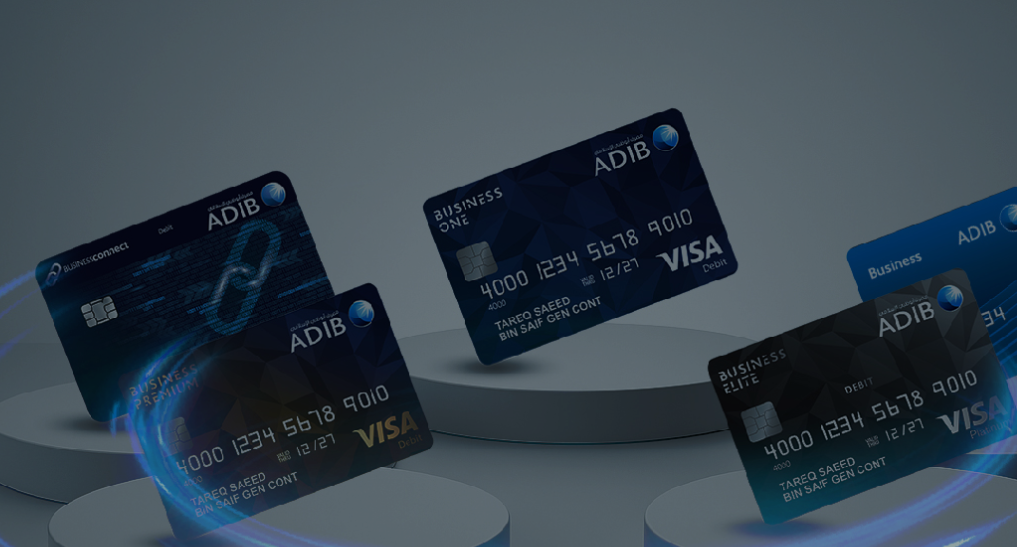
- Emirates Face Recognition: the ADIB Direct Business app verifies identity through EFR.
- Dirham account: Business Connect is held in AED only.
- ADIB Direct: ADIB's online and mobile banking platform, used both to apply and to bank.
- Monthly e-statements: free.
Pricing
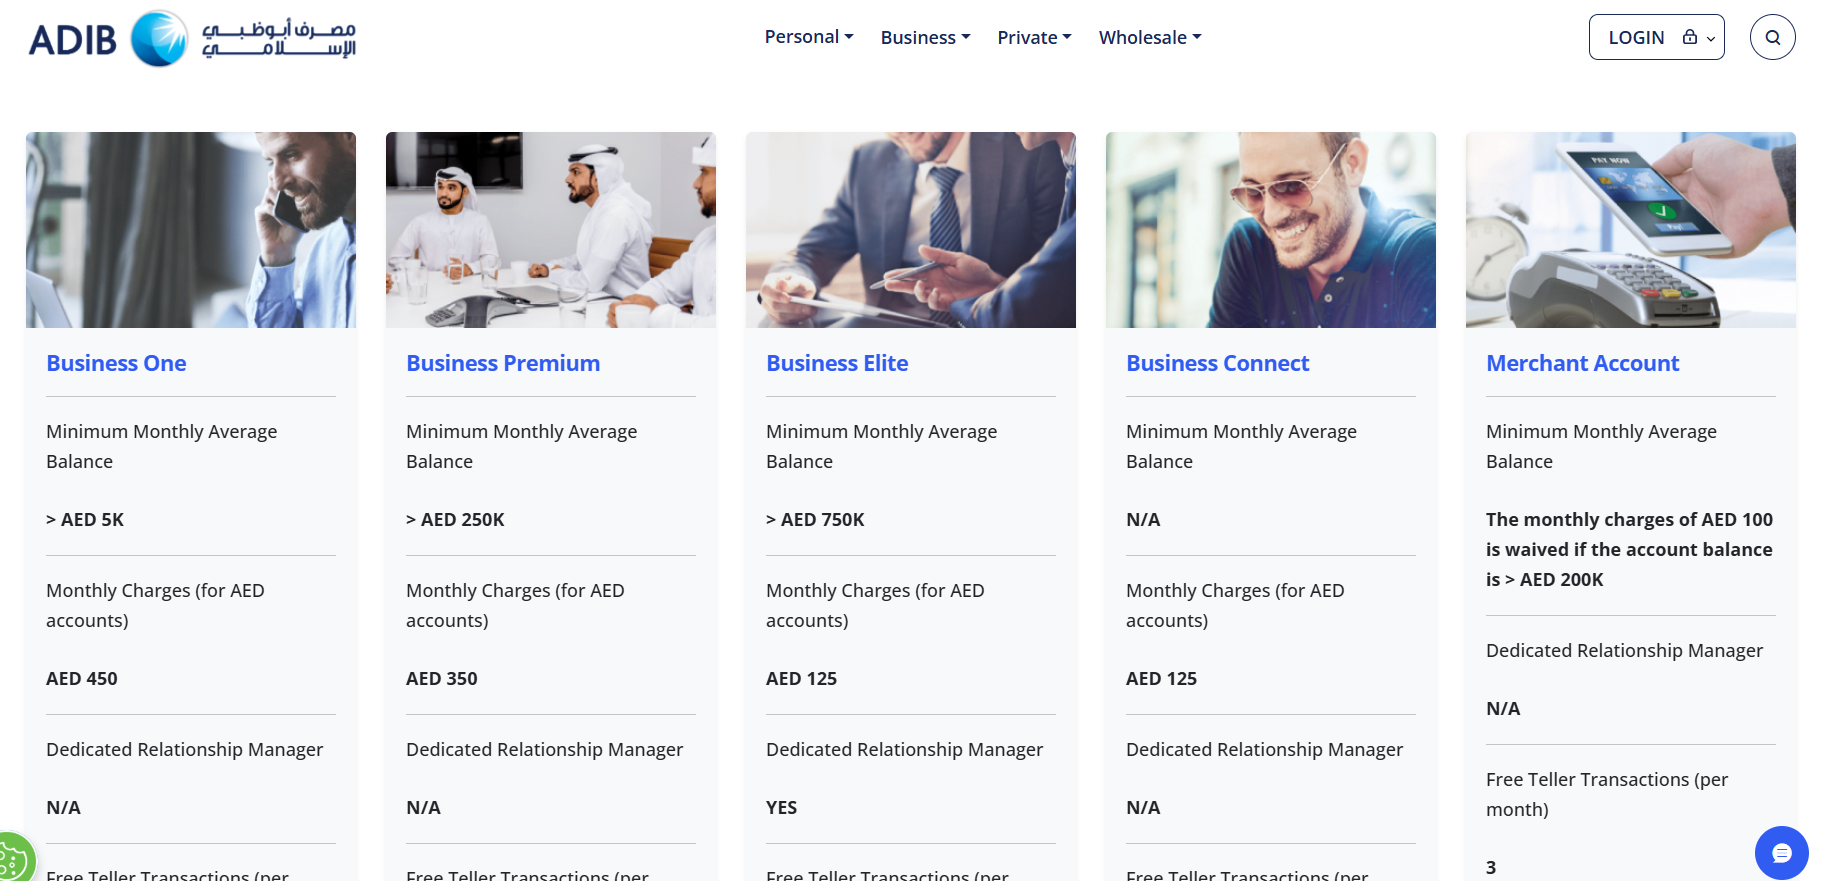
ADIB's package comparison page lists the minimum monthly average balance and the monthly charge for AED accounts:
- Business Connect: no minimum balance, a monthly maintenance fee of AED 125 per account, 1 free teller transaction a month, and AED 50 per additional teller transaction. Available only for business categories that meet ADIB's acceptance criteria.
- Business One: minimum monthly average balance above AED 5,000, monthly charges of AED 450, and 3 free teller transactions a month.
- Business Premium: minimum monthly average balance above AED 250,000, monthly charges of AED 350, and 7 free teller transactions.
- Business Elite: minimum monthly average balance above AED 750,000, monthly charges of AED 125, a dedicated relationship manager, 15 free teller transactions, and preferential FX rates.
- Merchant Account: AED 100 a month, waived when the balance is above AED 200,000, with 3 free teller transactions.
Pros and Cons
✅ Identity checked by face recognition in the app.
✅ A fixed AED 125 a month, whatever the balance.
✅ Monthly e-statements at no charge.
❌ Monthly charges run highest on the smallest tier: AED 450 on Business One above AED 5,000, against AED 125 on Business Elite above AED 750,000.
#8: Yuze
Best for: Solo operators and micro businesses that want an account open within a day, on Zand's banking.
Similar to: Zand corporate account, RAKBANK RAKstarter.
Yuze launched in 2022 as a business platform for freelancers and small companies.
Zand Bank PJSC provides every banking service in the Yuze app.
AI features
- Fast opening: most accounts open within 24 hours of an in-app application.
- Invoices with payment links: an invoice can offer payment by bank transfer or by a link that takes Visa and Mastercard.
- Analytics: a real-time view of inflows and outflows, including outstanding receivables.
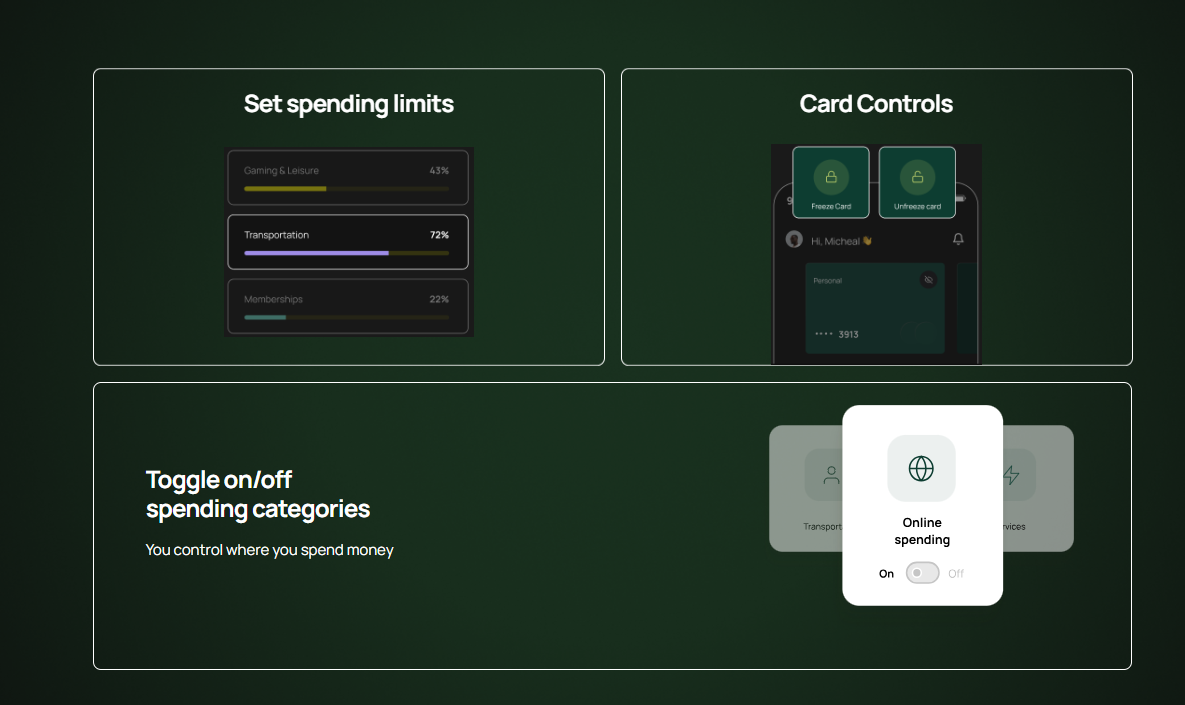
- Card controls: a virtual debit card on opening, which can be blocked instantly.
Pricing
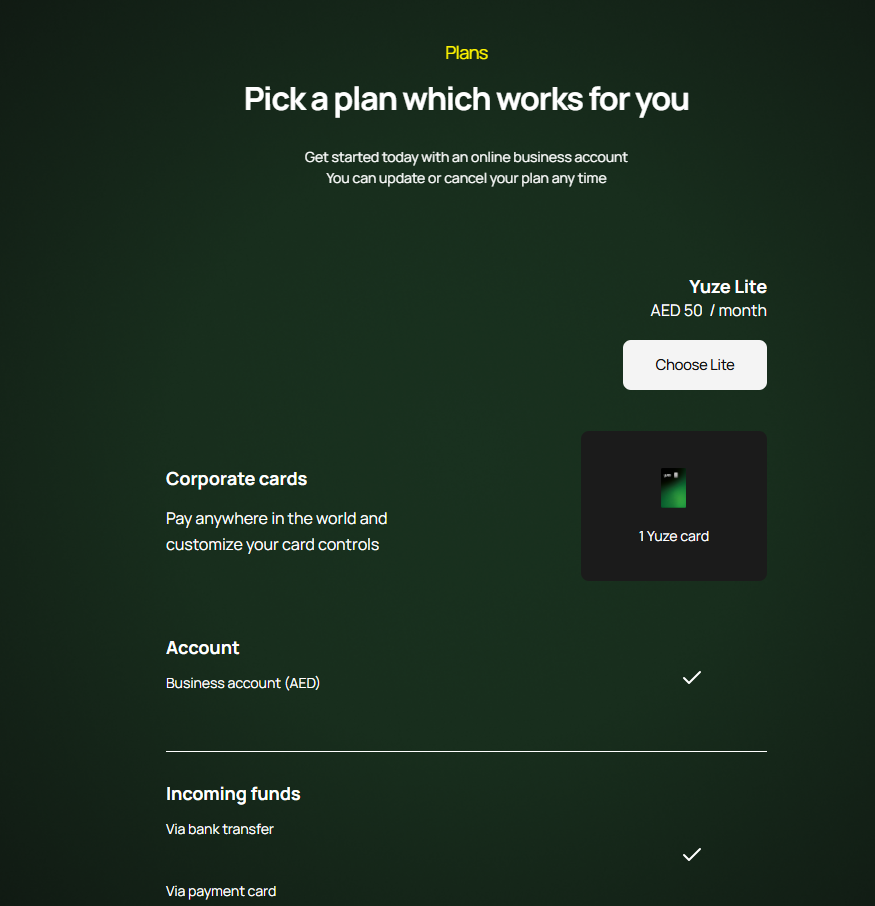
Yuze's UAE plans page currently lists one plan, which can be updated or cancelled at any time:
- Yuze Lite: AED 50 per month.
- Included in the plan: one Yuze card (physical and virtual), card controls, local transfers to banks and other Yuze customers, invoicing, payment links, spending analytics, and chat support.
- Joining fee: a one-time fee upon opening, according to Yuze's FAQ, with the amount not published.
Pros and Cons
✅ Most accounts open within a day.
✅ Invoices can carry a card payment link.
✅ Free zone companies are eligible.
❌ Local transfers only for now, according to Yuze's FAQ.
How can you test an account's AI before you apply?
You can start by finding out which stage of banking the AI covers, then try it on your own documents before you commit.
Five checks work across every provider here:
- Ask where the AI is used: onboarding, fraud checks, an app assistant, and payables each save time in different places.
- Check which app carries it: confirm the AI is available on your business login, since some banks document their assistant for the personal app only.
- Run a real supplier invoice through a demo: see what the AI extracts and what your team still has to type.
- Confirm who releases money: find out whether any payment can leave without a named person's approval and code.
- Check what reaches your accounting software: ask which fields sync and whether paid bills arrive marked as paid.
Our guide on how to open a business bank account in the UAE covers the documents a provider asks for at opening.
If AI isn't a requirement, our 10 best business bank accounts in the UAE compares a wider set of accounts.
Next steps: run a real invoice through Bill Pay
Most AI on this list helps at account opening or inside an app assistant.
The Pemo Business Account puts AI to work on the invoices that keep coming after that, month after month.
What your finance team gets:
- Invoice reading: Pemo's AI pulls details from uploads and forwarded supplier emails.
- Coding for review: suggested ledger categories and vendors from Pemo Copilot, ready for a quick check.
- One person releasing money: your POA, confirming each payment by SMS code.
- Wakala deposits on your schedule: tenors from one day to 12 months.
You can apply to open a Pemo Business Account or book a call with our team to see why over 10,000 companies in the MENA region have chosen Pemo.
⚠️ Disclaimer: This article was last updated on the 1st of October, 2026. Fees and AI capabilities come from each provider's published pages on that date and can change. Pemo is a financial technology platform and holds no banking licence; the Pemo Business Account is provided by ruya, a UAE-licensed bank. Expected profit rates are indicative and not guaranteed. This article is general information and not financial, legal, tax, or accounting advice. If there is any misinterpretation of the information, please contact us so we can fact-check it.
Frequently asked questions about AI business bank accounts in the UAE
Who licenses an AI business bank account in the UAE?
The Central Bank of the UAE licenses the bank that holds the account, exactly as it would for any business account.
Whatever AI the account offers is a software layer, whether the bank builds it in-house or a fintech builds it on top.
In the Pemo Business Account's case, ruya holds the licence and the IBAN, with Pemo supplying the software layer.
Can the AI release a payment on its own?
Not in the Pemo Business Account, where every payment waits for the POA's one-time SMS code.
With other providers, ask to see the approval flow in a demo before assuming how payments are authorised.
Is Pemo a bank?
No, Pemo builds the software around an account whose banking licence and IBAN come from ruya, a UAE-licensed Islamic bank.


